TalentCo HR Services LLP

How Can an Indian SME Move HR Operations from Spreadsheets to Software in Seven Days?

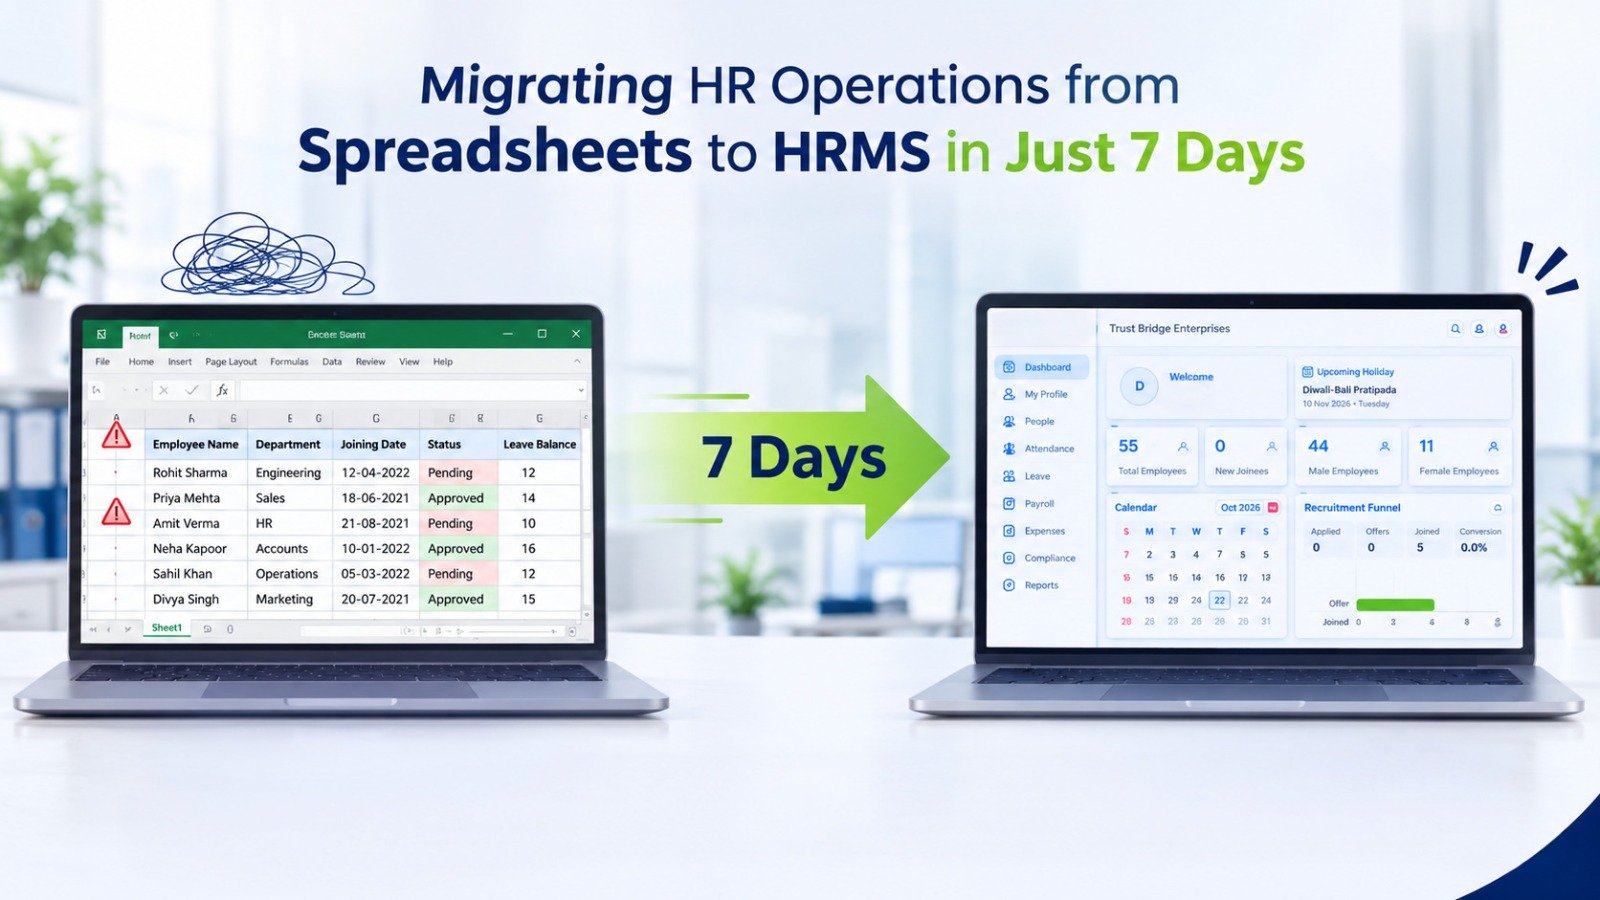
An Indian SME can move its core HR operations from spreadsheets to ABStart HRMS in seven days when employee records are prepared and the initial scope is agreed. ABStart’s process covers importing employee data, configuring attendance and leave policies, mapping salary structures, checking payroll inputs, onboarding users and switching on everyday HR workflows. By Day 7, employees can begin using digital attendance and leave requests, while the payroll setup has been checked against existing records before its first live processing cycle.

The seven-day plan below shows what the business needs to prepare, what happens on each day and how to keep day-to-day work running during the transition. More complex organisations can follow a phased rollout by location or workforce group.

What Should Be Ready Before the Seven-Day Migration Starts?

The most useful preparation happens before Day 1. A complete employee master and a clear person responsible for decisions prevent avoidable delays during configuration.

1.Employee master: Verify employee names, joining dates, work locations, reporting managers, relevant identity and statutory identifiers, and bank information.

2. Salary and payroll records: Keep current salary structures, applicable deductions, last month’s payroll output and any approved salary changes ready for comparison.

3.  Attendance and leave policies: Document shifts, weekly offs, holiday calendars, leave balances, approval rules and policies that differ by location.

4. Spreadsheet inventory: Identify the files currently used for employee records, attendance, leave, payroll and statutory reporting, including their owners.

5. Implementation owner: Nominate an HR contact who can answer policy questions, review imported data and approve the first live workflows.

Do not use migration as the moment to redesign every HR policy. Start with current approved rules, then plan changes separately after the system is stable.

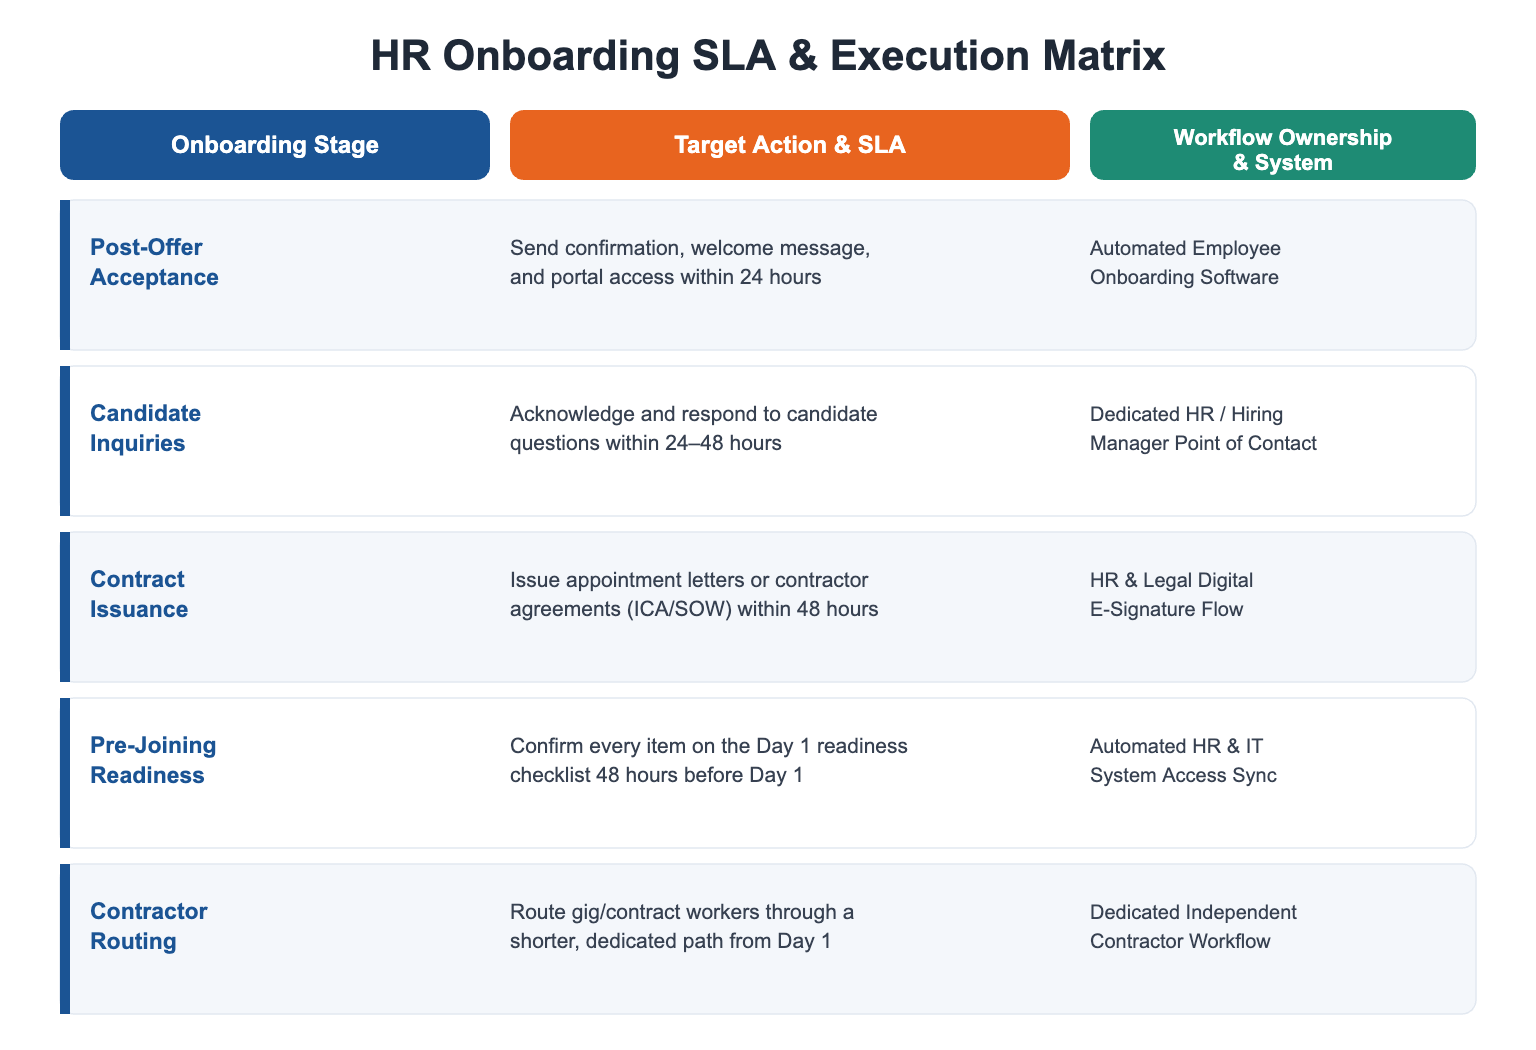
What Does the Seven-Day HRMS Migration Plan Look Like?
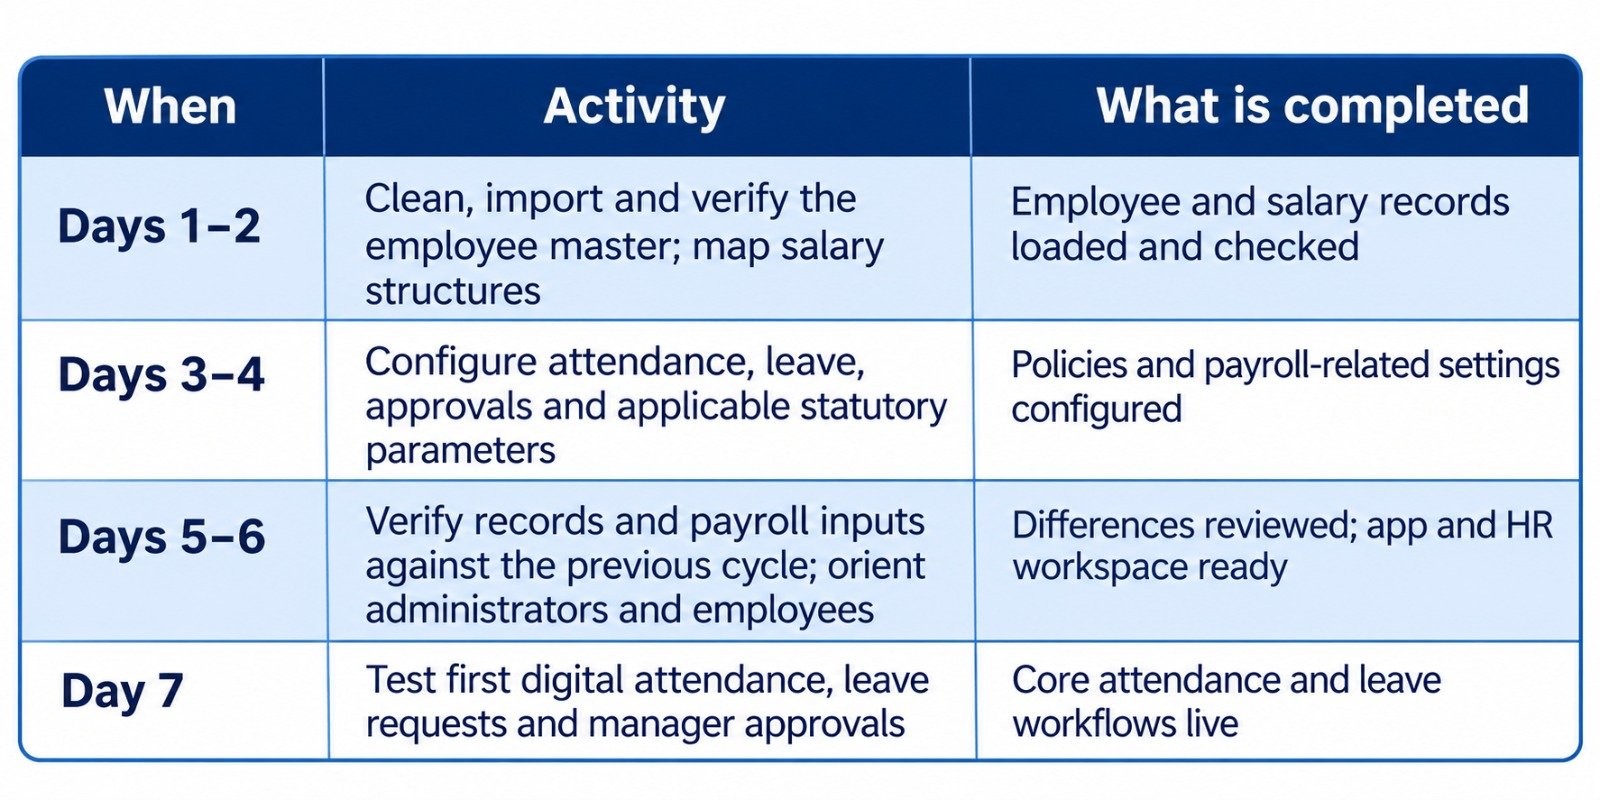
The Day 7 milestone is an initial operational go-live. Payroll settings and historical inputs are reconciled during the rollout; the first production payroll is run according to the employer’s normal payroll calendar and approval process.

What Happens During Each Stage?


Days 1–2: Import employee data and map salary structures

ABStart begins with the employee information already held in the organisation’s spreadsheets. The team prepares the import template, identifies missing or duplicate entries and maps salary components and deductions to the appropriate employee records. HR reviews imported data against the source files before it is accepted as the working record.

Days 3–4: Configure the policies employees actually follow

Attendance locations, shifts, leave rules, holiday calendars and approval responsibilities are configured to match the employer’s agreed policies. Where relevant, location-based or face-based attendance settings are included. Applicable PF, ESI, professional tax and salary TDS settings are reviewed for the workforce and locations involved.

Days 5–6: Verify the setup and introduce the employee app

HR and payroll owners compare the new records and payroll calculations with an existing payroll period, investigate differences and correct source data or configuration as needed. Administrators test their workflows, and employees receive short instructions for the actions they will use first. ABStart supports employee self-service on iOS and Android.

“Payroll errors are rarely just calculation errors. They often begin earlier, when a leave approval sits in a chat, attendance sits in a separate file, and salary details sit in a spreadsheet. Bringing these records together can reduce manual reconciliation and make payroll more accurate.”

Shailendra Dhamdhere, Founder, ABStart HRMS

Day 7: Start everyday HR workflows

Employees test digital punch-in and leave submissions. Managers verify that requests reach the right approvers. HR checks the activity records and keeps a nominated contact available for queries. Previous spreadsheets should be retained securely as reference records, with access limited to authorised personnel.

How Can SMEs Avoid Disrupting Daily Operations?

Use a controlled transition rather than switching every process at once. Keep the existing records available for verification while imported employee details, policy rules and payroll inputs are being checked. Explain to employees only the first tasks they need, such as marking attendance, requesting leave and accessing payslips when available.

Managers need a separate briefing on approval responsibilities and attendance exceptions. Field staff may also need instructions specific to their configured attendance method. Once records and workflows are confirmed, HR can establish which system is the official source for new transactions so that competing versions do not continue indefinitely.

Which Payroll, Data and Compliance Checks Matter Before Go-Live?

An HRMS helps organise information and apply configured rules, but employers remain responsible for verifying their policies and statutory obligations. Before relying on the migrated data, check the following against your current workforce and payroll records:

1. Payroll reconciliation: Employee headcount, salary structures, applicable earnings and deductions, leave balances and approved attendance exceptions.

2. EPF and ESI: Coverage and eligibility, employee identifiers, contribution settings, and the reporting or return requirements applicable to the establishment.

3. Salary TDS and professional tax: Applicable tax-year settings and forms, plus state-specific professional-tax treatment where required.

4. Access to employee information: Who may see or edit salary, identity, bank and personal data; how sensitive files are transferred and stored; and how past records are retained.

India’s four Labour Codes took effect on 21 November 2025, consolidating 29 central labour laws. The Income-tax Act, 2025 came into force on 1 April 2026. Employers should check current provisions and relevant state rules when configuring their processes, rather than assume a software setting alone establishes compliance. See the official Ministry of Labour and Employment announcement and Income Tax Department announcement.

Employee records also contain sensitive personal information. The Digital Personal Data Protection Rules, 2025 were published in November 2025 and have a phased commencement schedule. During migration, apply appropriate access restrictions and secure transfer practices, and review obligations as the relevant provisions come into force. See the MeitY DPDP Rules and enforcement timeline.

What Common Mistakes Can Delay HRMS Migration?

1. Importing employee records without checking duplicates, missing fields or out-of-date salary information.

2. Changing attendance or leave policies in the middle of the system migration.

3. Skipping the comparison of payroll inputs and calculated outputs with an earlier approved payroll period.

4. Giving too many employees access to payroll or personal information.

5. Leaving both spreadsheets and the HRMS open for uncontrolled editing after go-live.

The way to avoid these mistakes is straightforward: assign an owner, check source data, test the configured rules and confirm the system of record before moving into normal operations.

How Can Businesses Measure Success After Migration?

Review the first two payroll cycles rather than judging the change only by whether employees could log in on Day 7.

1. Payroll accuracy: The number and type of corrections needed after each cycle.

2. Month-end effort: The time HR spends consolidating attendance, leave and payroll information.

3. Adoption: Whether employees and managers complete expected attendance, leave and approval actions through the new system.

4. Statutory timeliness: Whether applicable returns and payments are completed according to the relevant deadlines.

If an issue persists, identify whether the cause is source data, configuration, approvals or user adoption, and address that specific step.

How Does ABStart Support the Seven-Day Transition?

ABStart was developed within TalentCo HR Services, drawing on practical HR, payroll and compliance experience. That experience shapes the transition from separate employee, attendance, leave and salary spreadsheets to connected HR workflows.

For a prepared SME, the seven-day rollout follows the same sequence described above: prepare and import employee data, configure existing policies, check payroll inputs, introduce the HR workspace and employee app, then activate everyday attendance and leave processes. The team works through differences found during verification rather than carrying unchecked records into the new system.

ABStart combines employee records, onboarding, attendance, leave, expenses, payroll and compliance workflows in one platform, with a web workspace for HR and self-service on iOS and Android. You can start with the functions your team needs immediately and add other capabilities as the organisation grows.

Considering a move from spreadsheets? Share your current employee records and HR process with the ABStart team, and book a walkthrough of the seven-day migration approach for your organisation.
Explore ABStart HRMS and request a demo

₹40 per employee per month. Check the pricing details for complete terms & conditions.

References and further reading

ABStart HRMS: product and implementation context

Ministry of Labour and Employment: four Labour Codes implementation

Income Tax Department: Income-tax Act, 2025 commencement

MeitY: Digital Personal Data Protection Rules, 2025 and enforcement timeline

EPFO: employer portal and filing information


This article is for general information. HRMS configuration should reflect current applicable laws, rules and approved company policies.
Which HRMS features do Indian SMEs actually need?

Is your HRMS built for the business you run today, or the one you might become?

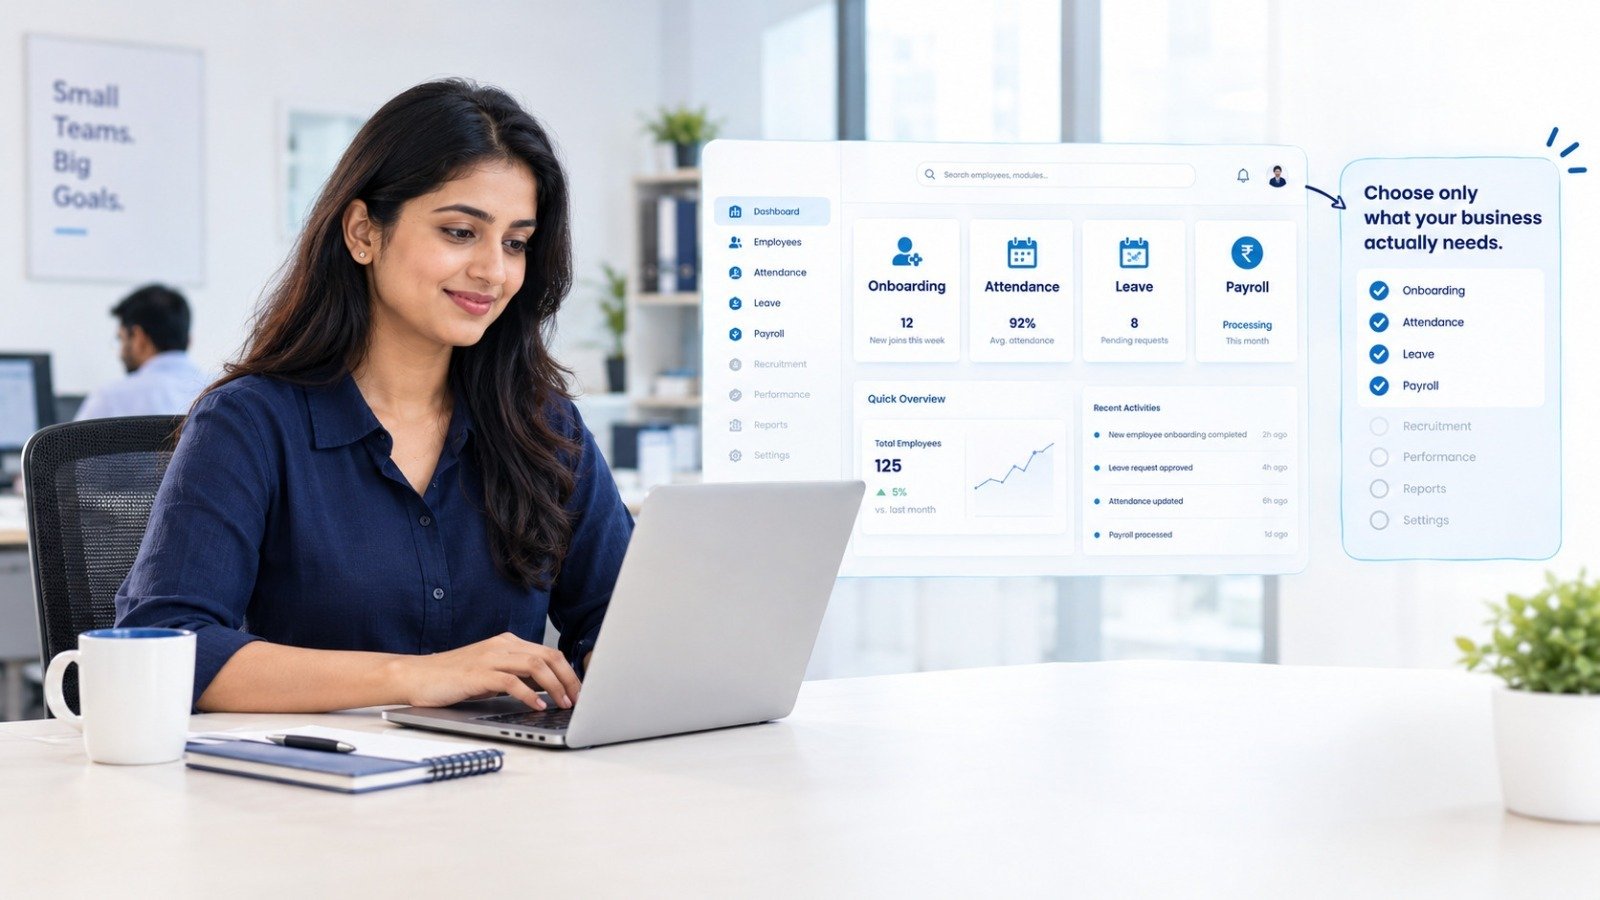
Choosing HRMS features for Indian SMEs usually starts with a list of everything the software can do. It should start with a usage question instead: which of these features did your team open last month?

There is no single feature set that fits every Indian SME. In practice, the monthly work sits in a small core — onboarding, leave, attendance and payroll — with statutory compliance alongside payroll wherever the company files PF, ESI or professional tax itself. That core is the floor, not the answer. What you add above it, from performance management to recruitment to training, depends on how much of that work your team actually does and how complex your workforce is.

Many Indian SMEs pay for features nobody opens. It rarely comes down to a bad decision. The vendor quotes a bundle, the demo shows every module, and the founder picks a plan that will still fit when the company has twice as many people. A year later, a good part of that plan sits idle. The industry has a word for it: shelfware — software that is licensed, implemented and never used.

In the HR reviews our team runs with SME clients, the same pattern keeps appearing. The modules that go quiet are rarely the ones doing daily work. They are the ones bought for a stage the company had not reached yet: performance management before there was a review cycle, recruitment before hiring became continuous, training before anyone owned it. Attendance, leave and payroll are opened every day — and they still cause most of the month-end pain when they are configured badly.

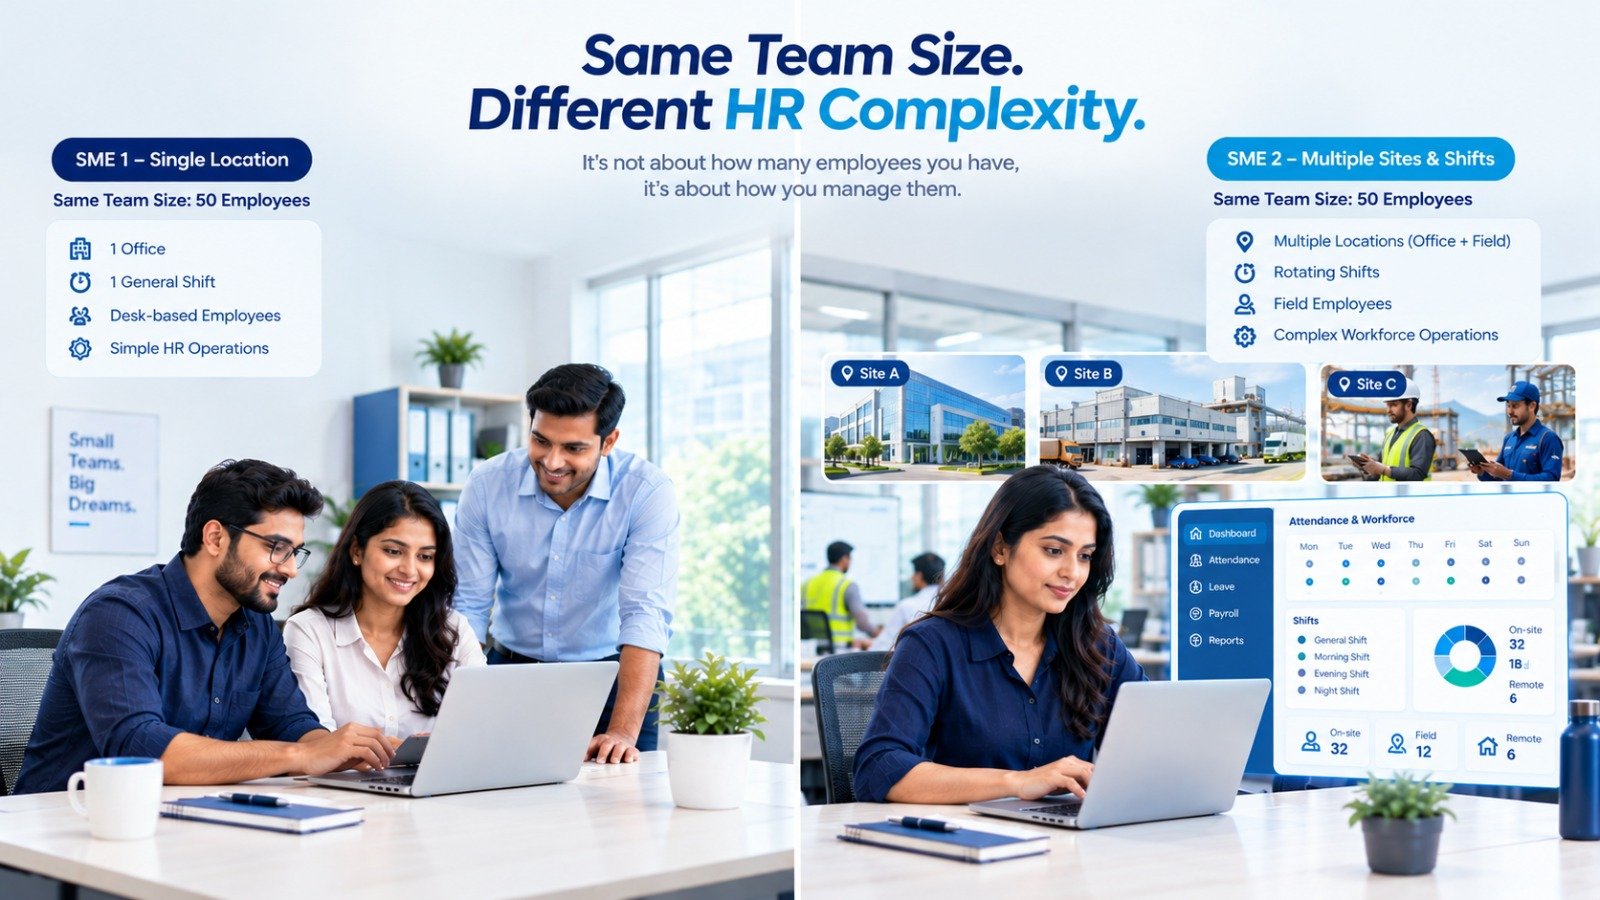
Not every SME ends up here. A 60-person company with three shifts and four sites may need more configuration than a 150-person company in one office. The complexity of the workforce matters more than the headcount.

Why do growing Indian SMEs end up paying for HRMS features they rarely use?

Many SMEs select a plan based on anticipated growth rather than current operational requirements. Four things push them there.

Some vendors only sell modules as a bundle, so a company that wants payroll ends up paying for performance management too. Demos go through every feature, and the full package starts to look like the normal starting point. Founders buy for the headcount they expect next year rather than the payroll they run this month. And without a periodic usage review, nobody notices the gap until renewal — when migration, training and implementation costs make switching harder.

Vendors can explain what their platform does. Only you can say whether that capability matches your workflows, your policies and what your team does every month.

Does a 90-employee company need the same HRMS as a 900-employee company?

No. The right HRMS depends on workforce structure, operating locations, shift patterns and payroll complexity, not on employee count alone.

Take two companies with 90 employees each. One has a single office, one general shift and fixed monthly salaries. It needs attendance, leave and payroll that work, and very little else. The other has four sites, rotating shifts, field staff who mark attendance from client locations, overtime rules, and contract workers paid by the day. That company needs shift rules, location-based attendance and flexible pay components — and it will use them every month.

A 900-person company is not a different species. It usually has more of the same problems: several legal entities, layers of approval, a compliance calendar that varies by site, and payroll that has to reconcile across locations. The core modules do not change. What changes is governance — who approves what, how exceptions are handled, and how much configuration the system has to carry.
What do unused HRMS features actually cost a business?

More than the monthly fee. Each module has to be configured and tested, and someone has to train users on it and keep it current even when nobody uses it much.

Three things get confused here, and the distinction matters when you audit. An unused licence is a seat you pay for that nobody uses — a duplicate account, a user who has left, or a name added just in case. An unused module is one that sits in your plan with no activity: either never switched on, or switched on and abandoned. An infrequently used feature is different again. Full and final settlement, annual appraisal, the bonus run — these can sit idle for months and be entirely justified, because the process they support happens once or twice a year.

Only the first two are waste. A module that arrives bundled at no extra cost and is never used is not a billing problem — it is a training and complexity problem, and still worth taking out of the next demo.

The arithmetic is simpler than the invoices make it look, and it has three parts: the share of the licence that pays for modules with no activity, the setup fee already spent on them, and the hours your team spends each month keeping them current. Take a company on a ₹2,40,000 annual subscription, as an example. If a quarter of the licence — ₹60,000 — covers modules with no activity over the last three months, that is ₹60,000 a year before the setup fee and the admin hours. Both figures are illustrative, not a market rate. The ratio is what matters: if a quarter of the bill buys nothing, that is the conversation to have before renewal.

The first thing we ask for in a review is the usage report, not the contract. A contract tells you what you are entitled to. Usage tells you what you are getting.

The larger cost arrives at renewal. A team that has spent a year with dormant modules has also built its month-end around a system it may not want to keep. Switching then means migration, retraining and a parallel run — so most companies renew rather than right-size. That is why the decision belongs 90 days before renewal, not after it.

How do you run an HRMS utilisation assessment?

A utilisation assessment is a half-day exercise, not a consulting project. Five steps, in this order.

1. Pull the module-level usage report for the last 90 days. Logins and transactions, not just user counts — a module can have active users and no work.

2.Match each module to the process it supports and how often that process runs. Monthly payroll and annual appraisal need different baselines, so judge each against its own cadence.

3.Split seats into active users, provisioned accounts and leavers. Duplicate and dormant accounts are the cheapest thing to fix.

4.Price the gap: the share of the subscription with no activity, the setup already spent on it, and the hours your team spends each month on those modules.

5.Take the list to renewal. Reduce seats, remove or downgrade a module, and check the notice period before you sign anything.

Which HRMS capabilities matter most in everyday HR operations?

For most SMEs, the daily work sits in attendance, leave, payroll and onboarding, supported by reliable data sharing across modules. Statutory compliance — PF, ESI, professional tax, TDS — is a function those modules have to serve, whether it arrives as a separate module or as part of payroll. 

Onboarding creates the employee record. Attendance and leave record what happened during the month. Payroll uses both to calculate pay, and expense claims get added on top. When these modules share consistent employee data, authorised updates flow across relevant processes, reducing duplicate entry and the risk of discrepancies.
Here is how that shows up in practice, and where the month-end pain usually starts. A salary revision during the month may require payroll to calculate earnings using the applicable rates for each period; the final figure depends on the effective date, company policy and payroll configuration. If the joining date is entered differently in onboarding and in leave, accrual and loss-of-pay days can come out differently. A missed punch approved after the payroll cut-off may be recovered as an arrear in the next cycle, depending on policy. Offices in different states follow different holiday lists, and weekly-off patterns vary by site, so even the count of working days changes.
Well-integrated core HR functions, with clear workflows and an interface people actually use, do more for an SME than a long feature list.

What should SMEs check before buying or renewing an HRMS?

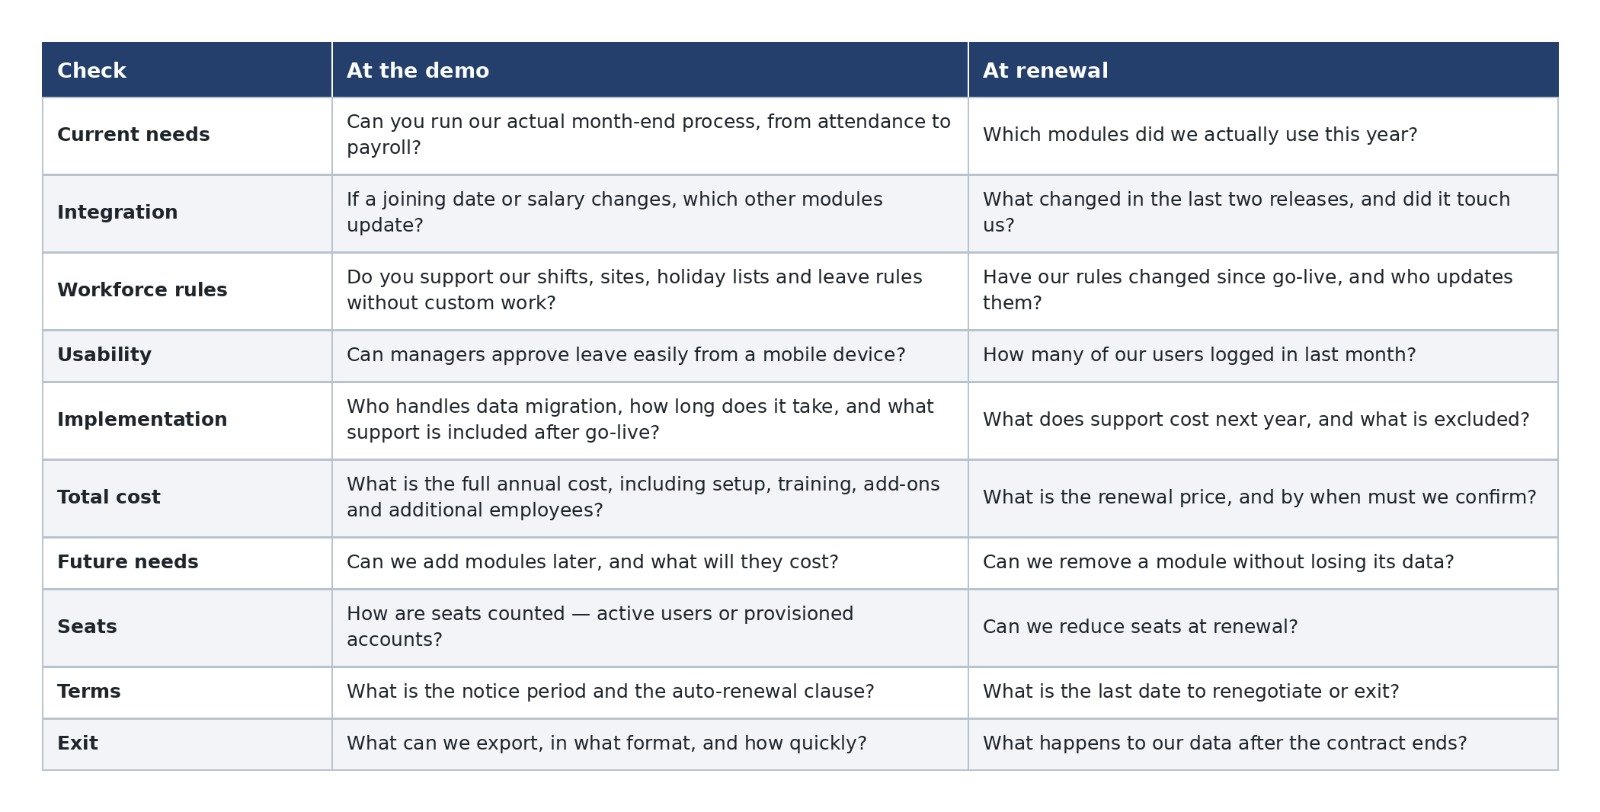
Start with how your team works today and test the software against that. The same checklist works at demo stage and again at renewal, where the questions change from capability to utilisation and terms.
If you are still shortlisting, the longer version of the first column sits in our guide to choosing an HRMS for your Indian SME. If you are deciding whether you need one at all, the statutory thresholds that force the decision are covered separately. 
How can growing businesses choose an HRMS that supports their next stage?

Choose one that meets your current requirements and offers a clear, costed path to adding capability later.

Look for modules that share one employee record. Read what each plan includes, line by line. Ask whether extra modules can be added without moving your data — and whether they can be removed without losing it. A company can start with the core and add more when a real need shows up; that is the argument for a modular system over a bundle.

What does HR leadership add to an HRMS?

Most HRMS vendors sell a product and a support ticket. The decisions that determine whether the system works — how leave rules, shifts, salary structures and statutory obligations are configured — are left to the buyer, or to a product specialist working through a checklist.

ABStart begins from the other end. It was built and incubated inside TalentCo HR Services, an HR consulting and solutions firm, by founder Shailendra Dhamdhere and a leadership team with more than three decades of experience across people operations, payroll, compliance and organisational advisory.  More than 100 growing companies already work with TalentCo on people, payroll, compliance and advisory.

So you are not only buying modules. The people who configure leave rules, shifts and salary structures come from that HR practice — they have run payroll, managed statutory compliance and written leave policies — rather than only from a product helpdesk. That is the most practical defence against over-buying too: someone who has run a 90-person month-end can tell you, before you sign, that performance management can wait a year.

ABStart itself brings the core functions together on one platform: onboarding, leave, attendance, expenses, payroll and compliance. The SME plan starts at ₹99 per employee per month for that core set, and the final cost depends on your headcount, the modules and the support you add — a 60-person company with three shifts is not quoted the same way as a 200-person company in one office. 

Key takeaways

1. Start from the work, not the list. The core is onboarding, leave, attendance and payroll — a floor, not a complete answer. Workforce complexity decides what sits above it.

2.Three different things. An unused seat, an unused module and an occasional feature are three different problems, and only two are waste.

3.Measure before you renegotiate. Audit usage once, before renewal, using the usage report rather than the contract.

4.Add on evidence. Buy the core first and add modules when the work arrives, not when the roadmap says so.

Frequently asked questions

Is an HRMS worth it for a 50-employee company?

Usually, but not because of the subscription. At 50 people the subscription is rarely the line item that hurts; a payroll error, a late PF deposit or a compliance notice is. What decides it is whether the system replaces recurring manual work — attendance, leave and payroll — and whether the modules you buy match how your team actually works.

How much does an HRMS cost for an Indian SME?

Headline rates are usually quoted per employee per month, but the number that matters is the annual quote for your headcount and module set. Ask for a scoped quote that includes setup, support and any per-employee minimum, then compare totals rather than headline rates. ABStart’s SME plan starts at ₹99 per employee per month for the core set.

What is HRMS shelfware, and how do I find it before renewal?

Shelfware is software you license, implement and never use. Find it with a module-level usage report: list every module you pay for, the last date anyone logged in, and the process it supports. Anything with no activity in 90 days, and no process on your calendar that needs it, is either waiting to be switched on or unnecessary.

Do Indian SMEs need performance management and recruitment modules?

Only when the work is continuous. Performance management earns its place when there is a review cycle with goals and ratings; recruitment when hiring never really stops. Before that, they add configuration and training without changing a month-end. If a bundle includes them at no extra cost, the question is whether they are worth the admin time, not the licence.

Make every HRMS investment count

The value of an HRMS depends on how well its capabilities align with your business processes, workforce requirements and budget.

Before the next renewal or expansion, write down what your team uses every month and what was never switched on. Note what is still done in Excel. Then compare that list with your current plan.

Want to see how your everyday HR workflows could work on one platform? Book a free ABStart HRMS demo and evaluate attendance, leave and payroll against your business requirements.

References and further reading

[1] ABStart HRMS — module set and plan structure: https://talentcohr.com/abstart/

[2] TalentCo HR Services, Payroll Compliance in India for SMEs: https://talentcohr.com/payroll-compliance-in-india-for-smes/

[3] TalentCo HR Services, Statutory Thresholds for Indian SMEs: https://talentcohr.com/statutory-thresholds-sme-hrms-india/

TalentCo HR Services LLP is an HR consulting and solutions company offering services across HR operations, compliance, payroll management, and HR technology through its proprietary platform ABStart. This article is for general information only; plan details and pricing may change, so confirm current information on the ABStart page. Verify current regulations or consult a qualified professional before making business decisions.

What Is the Legal Difference Between Section 194C (1023) and Section 194J (1027) TDS Deductions for Contractor Onboarding?

What Is the Difference Between Section 194C and Section 194J?

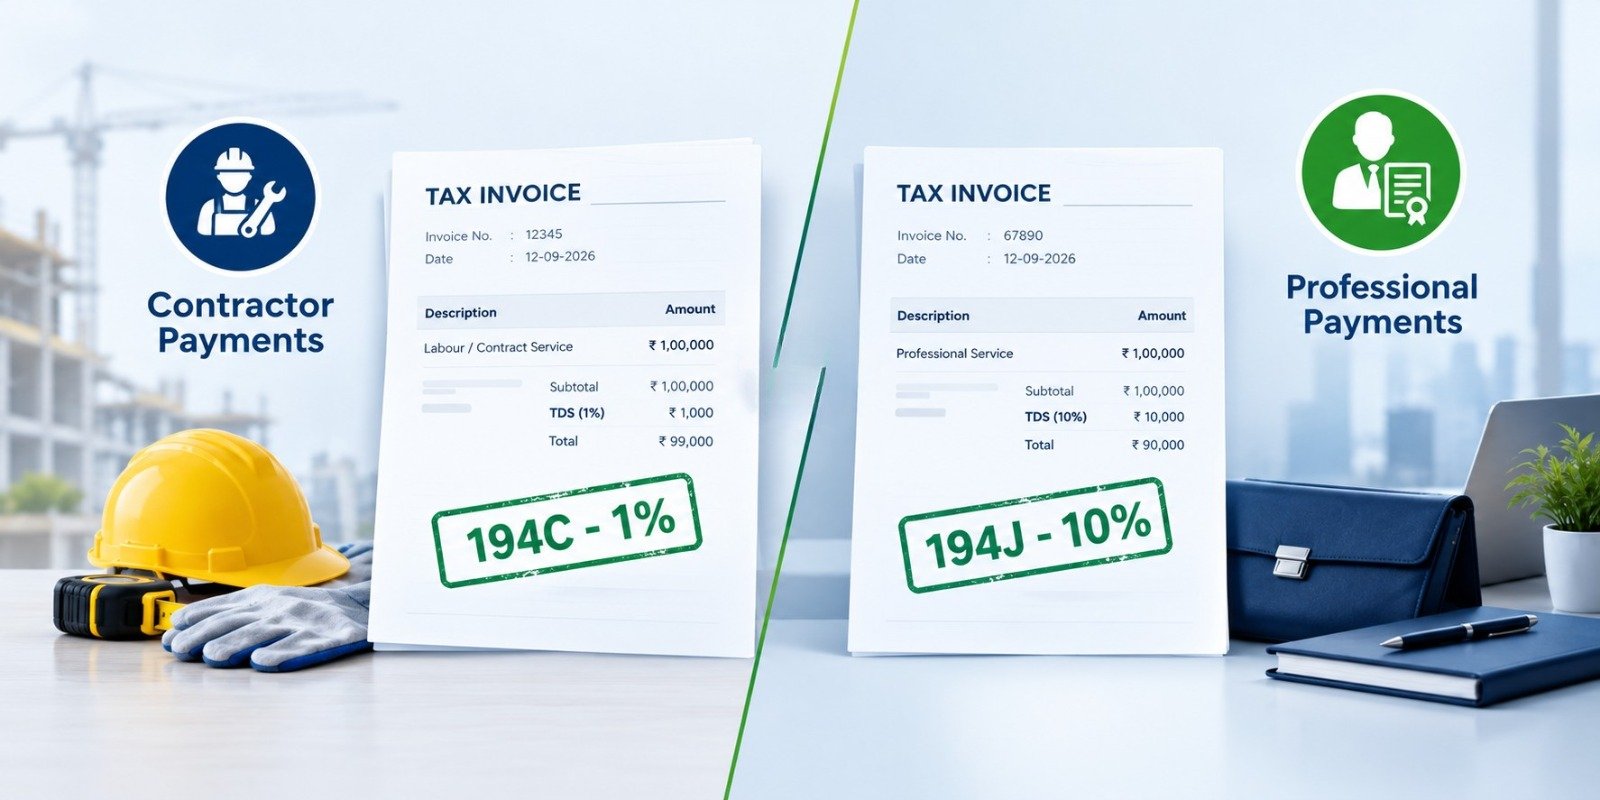
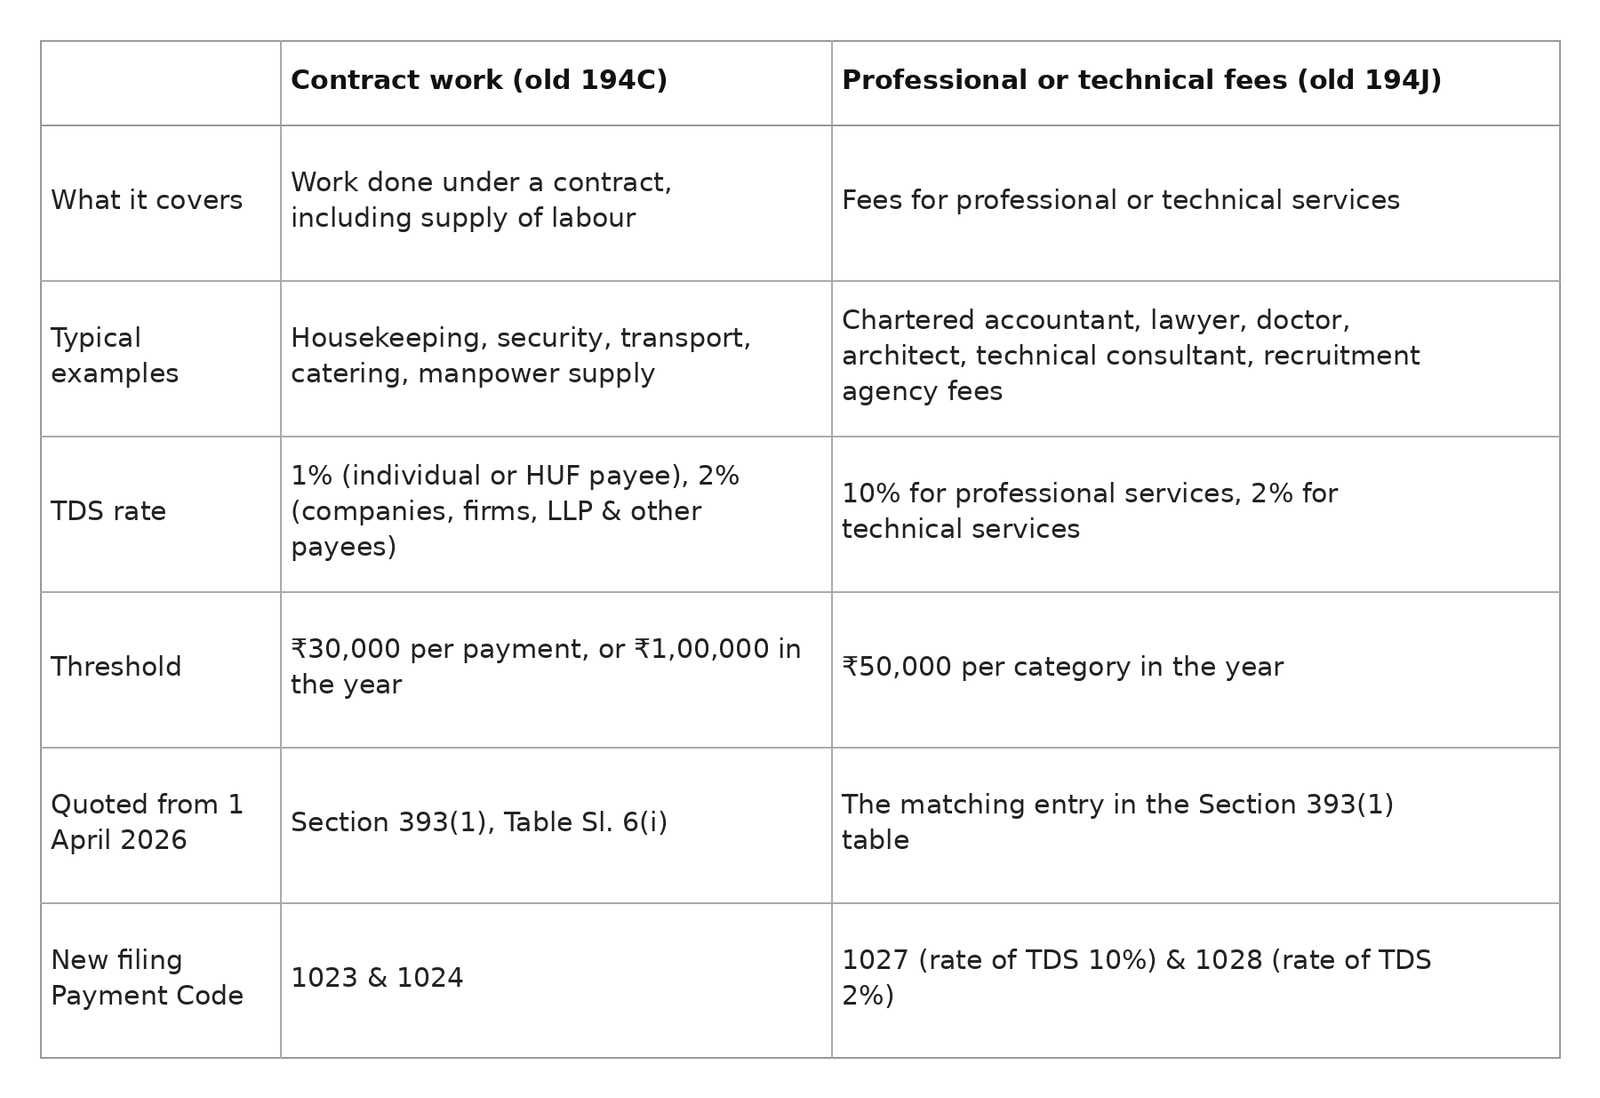
Section 194C covers payments for work done under a contract, including supply of labour. Section 194J covers fees for professional or technical services. The rates differ: 1% or 2% under 194C, and 10% or 2% under 194J. From 1 April 2026, both sit under Section 393 of the Income-tax Act, 2025. The rates and thresholds carried over.

Most confusion comes from vendors who sit between the two. A staffing company, a software vendor, and a recruitment agency all “provide services”, but the TDS treatment is not always the same.

How Do You Decide Which One Applies?

Ask what you are paying for. If the vendor delivers work, labour or a routine service, it is contract work. If you are paying for expert skill or advice, it is a professional or technical fee. The agreement and scope of work decide this, not the vendor’s name or the invoice heading.

Three questions help on a first pass:

1. Is the vendor doing a task or supplying people? Cleaning, security, transport, catering and manpower supply usually point to contract work.

2. Is the vendor a professional, or giving expert advice? Legal, medical, architecture, accountancy and technical consultancy usually point to professional or technical fees.

3. Does the invoice mix both? Split it by component. Do not apply one rate to the whole invoice.

Since October 2024, the definition of “work” under 194C leaves out payments that fall under 194J. A payment cannot be both.

What Does This Look Like With Real Numbers?

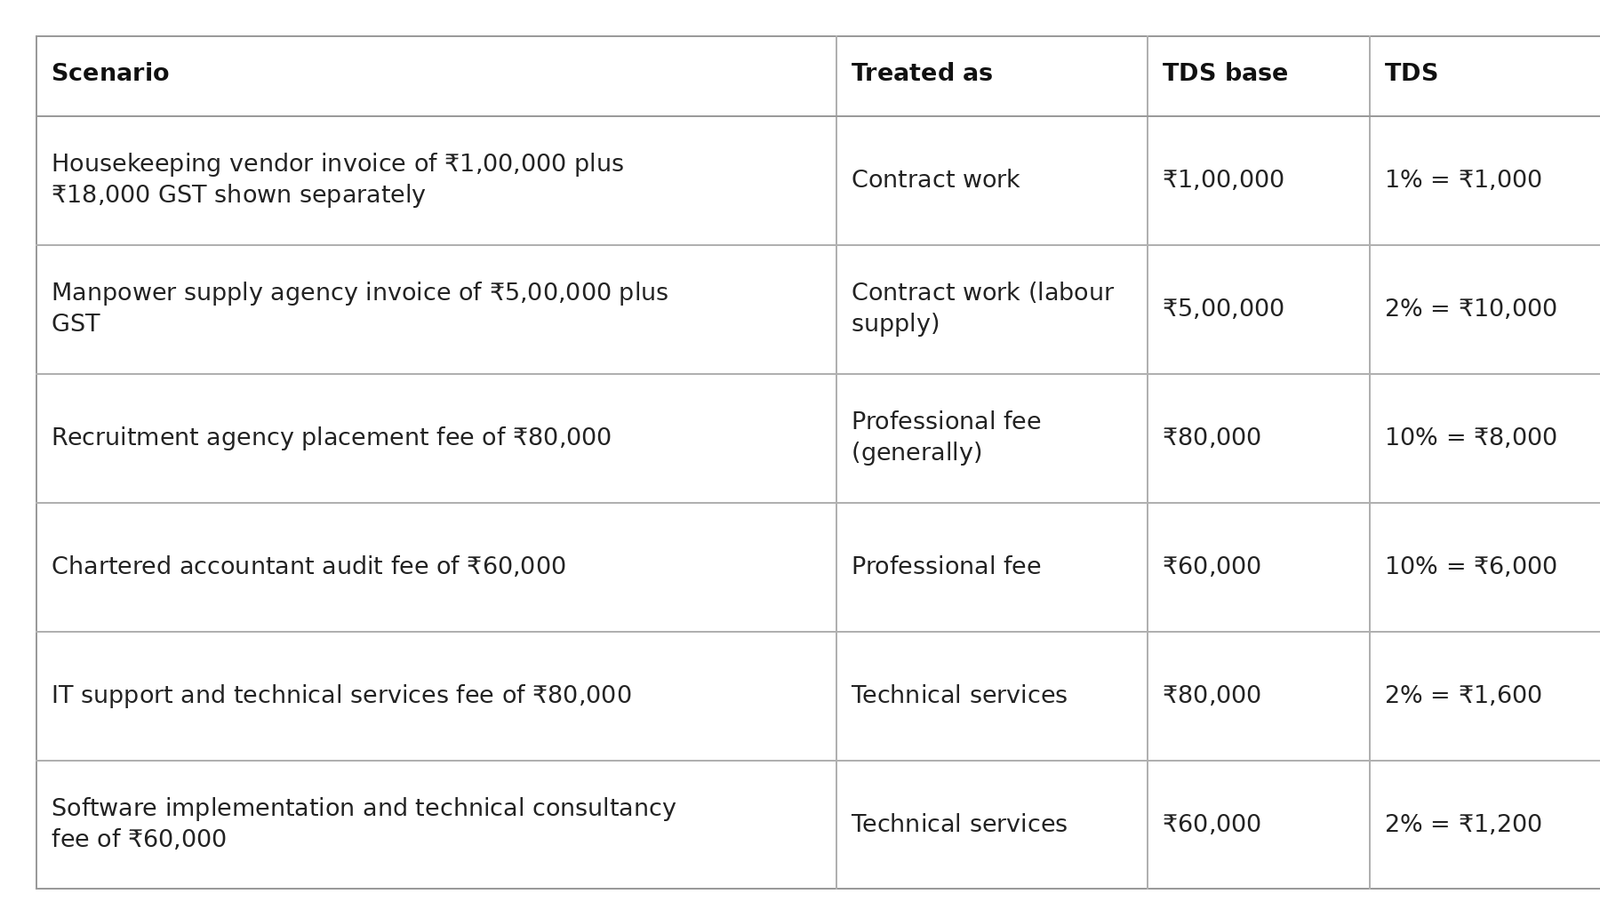
These examples assume the payee is a company or firm, and that the thresholds have already been crossed.

Take the manpower invoice. If someone applied the 10% professional rate by mistake, ₹50,000 would be deducted instead of ₹10,000. The vendor would be short by ₹40,000 and would ask for a correction. If the mistake runs the other way, the deductor is short-deducting, which is the costlier error.

What Changed on 1 April 2026?

The Income-tax Act, 2025 replaced the 1961 Act for payments credited or paid on or after 1 April 2026. Sections 194C and 194J are now table entries under Section 393(1). Rates and thresholds did not change. TDS returns must quote the Section 393 entry, not the old section number.

What this means in practice:

1. Payments credited or paid before 1 April 2026 stay under the old Act and the old section numbers.

2. For payments on or after that date, the Income Tax Department says to quote the relevant Section 393 table item. For contractor payments, its own example is Section 393(1), Table Sl. 6(i).

3. Quoting 194C or 194J for these payments can cause system validation errors and corrective filings.

Check that your accounting or payroll software has been updated to map vendor categories to the new entries.

What Mistakes Do Finance Teams Make Most Often?

1. Classifying by the vendor’s name. “Agency” does not automatically mean 194J, and “consultant” does not automatically mean professional fees.

2. One rate for a mixed invoice. Routine work and a consulting component need separate treatment.

3. Missing the annual threshold. Several invoices below ₹30,000 can add up past ₹1,00,000 in the year, and TDS then applies.

4. Deducting on the GST-inclusive amount. Where GST is shown separately on the invoice, TDS is calculated on the amount without GST.

5. Using old section numbers on returns for payments made after 1 April 2026.

A wrong classification leads to short deduction, which means tax shortfall and interest. The expense can also be disallowed. The bigger risk is repetition: if the same wrong treatment is applied to 40 vendors, the error repeats 40 times.

“Most classification errors we see aren’t carelessness — they’re a company applying one rate to every vendor because nobody separated ‘work’ from ‘expertise’ at the onboarding stage. That one decision, made correctly once per vendor, prevents almost every dispute we get called in to fix later.”

— Shailendra Dhamdhere
Founder, TalentCo HR Services

What Should You Do When Onboarding a New Contractor or Vendor?

1. Collect the basics. PAN, GST details and a signed agreement with a clear scope of work.

2. Classify before the first payment. Decide contract work or professional/technical fees. Write one line explaining why and keep it with the vendor record.

3. Track payments through the year. Keep a running total per vendor so the thresholds do not surprise you at year-end.

4. Review the first invoice. Split it if it mixes services, and calculate TDS on the amount excluding separately shown GST.

5. Quote the correct Section 393 entry when filing, and reconcile deductions against the quarterly return.

How Does Contract Staffing Change the TDS Picture?

When you hire through a contract staffing company, the workers are on the agency’s payroll. You receive one invoice for the service, so the TDS decision is made once, at the vendor level. It is generally treated as contract work, but confirm this against your agreement with your CA.

Engaging freelancers or individual contractors directly is different. Each person needs their own PAN, agreement, classification and threshold tracking. Companies with many such engagements often find it easier to route them through a staffing partner. TalentCo’s contract staffing service covers onboarding, payroll support, statutory compliance and documentation for contract staff.

 Talk to TalentCo About Contract Staffing


References

[1] Income Tax Department, e-Filing portal, Tax Payments help page (transition to the Income-tax Act, 2025; quoting Section 393 table items): https://www.incometax.gov.in/iec/foportal/help/all-topics/e-filing-services/tax-payments
[2] India Briefing, “Section 393 of Income Tax Act 2025 Explained: FAQs for Deductors”: https://www.india-briefing.com/news/section-393-income-tax-act-2025-tds-rules-rates-compliance-guide-44450.html/

TalentCo HR Services LLP is an HR consulting and solutions company offering HR operations, compliance, payroll management, contract staffing and recruitment services. This article is for general information only. Tax laws and TDS provisions may change. Please consult a qualified chartered accountant or tax professional before deciding the TDS treatment for a specific payment.

How Can HR Teams Eliminate WhatsApp-Based Leave and Payslip Requests Without Increasing Software Costs?

Why Do Leave and Payslip Requests End Up on WhatsApp in the First Place?

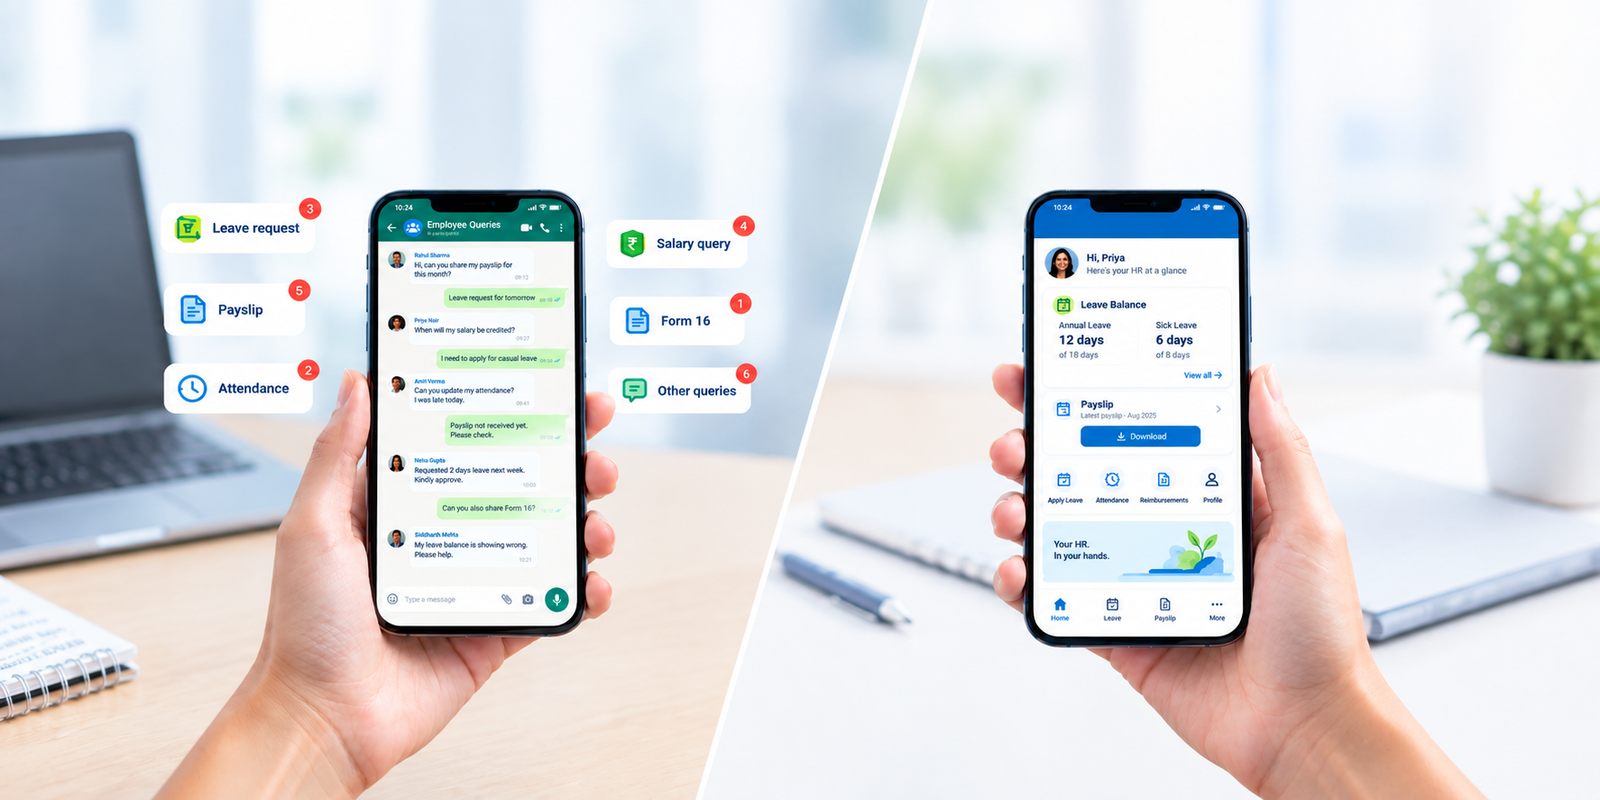
Employees use WhatsApp because it’s faster than emailing HR or filling a form nobody checks regularly. HR ends up managing two systems at once: the official process and the informal one everyone actually uses. The fix isn’t banning WhatsApp — it’s giving employees a self-service option that’s just as fast.

This pattern rarely starts as a policy decision. It starts small — one employee messages HR directly because they’re travelling and can’t access the portal, HR responds quickly to be helpful, and within a few weeks that becomes the default channel for the whole team. By the time it’s noticed, it’s not one employee’s habit; it’s the entire company’s unofficial process.

What Does WhatsApp-Based HR Actually Cost an HR Team Day-to-Day?

1. Constant interruption — leave requests, payslip queries, and document requests arrive throughout the day with no queue or priority order

2. No audit trail — an approved leave on chat has no timestamp, no record tied to the employee’s official leave balance

3. Duplicate work — HR checks WhatsApp, email, and the official system separately, then manually reconciles all three

4. Payslip requests repeat monthly — the same request, from the same employees, every single cycle, answered each time manually

5. Inconsistent approvals — a leave approved in a WhatsApp chat carries no record of who approved it or when, which becomes a problem the moment there’s a dispute

None of these costs shows up on an invoice, which is exactly why they persist. They’re absorbed as “part of the job” rather than tracked as time lost — but the hours spent answering the same handful of requests every day add up to a significant share of an HR operations role.

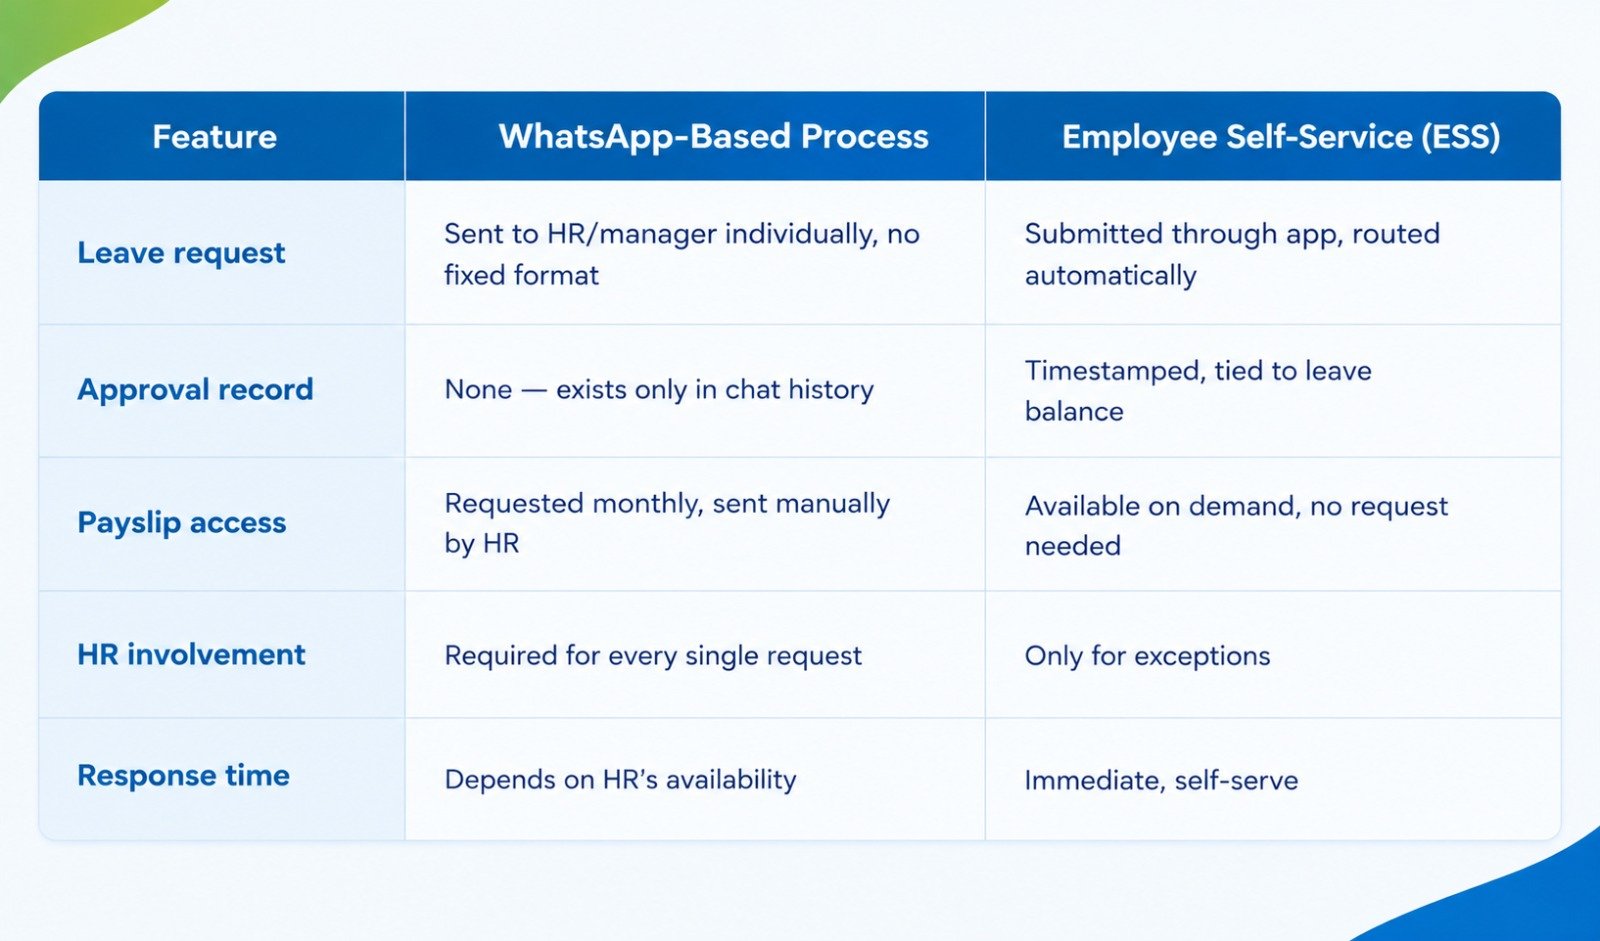
WhatsApp Requests vs. Employee Self-Service: What Actually Changes?

Can HR Teams Fix This Without Buying New Software?

Yes, if the existing HRMS already includes an Employee Self-Service (ESS) module that isn’t being used. Most mid-sized HR systems in India come with ESS built in — leave application, payslip download, and document requests — but many companies never activate it, or employees were never trained to use it, so WhatsApp filled the gap by default.

Before evaluating new tools, it’s worth checking the current HRMS contract or admin panel for an unused ESS or employee-portal feature. It’s common for companies to pay for a tier that already includes this, without anyone on the HR team realising it was part of the package.

“Most HR teams don’t realise they’re already paying for the fix. Employee self-service usually sits unused in the same HRMS licence they signed up for — WhatsApp fills the gap simply because nobody activated the feature or trained employees to use it.”

— Shailendra Dhamdhere
Founder & Managing Director, ABStart HRMS

What Steps Actually Move Employees Off WhatsApp?

1. Audit whether the current HRMS already includes ESS, before assuming new software is needed

2. Migrate one function at a time — start with payslips, since it’s the highest-volume, lowest-resistance request

3. Set a hard cutoff date after which WhatsApp requests are redirected to the ESS link, not answered directly

4. Send payslips and leave balance updates through the ESS app’s own notifications, so employees have a reason to open it

5. Track adoption weekly for the first month, and follow up individually with employees still messaging HR directly

The hardest part of this shift isn’t technical — it’s behavioural. Employees will keep messaging HR directly as long as doing so still works. The moment HR stops responding to WhatsApp requests and redirects to the portal instead, adoption typically follows within a few weeks, not months.

Why Does Starting With Payslips Work Better Than Starting With Leave?

Payslip requests are repetitive, predictable, and carry no approval decision — an employee wants their payslip, not a conversation. Leave requests, on the other hand, often involve a manager’s approval and some back-and-forth, which makes them a harder first habit to break. Moving payslips first proves the ESS system works before asking employees to trust it with something that needs approval.

There’s also a trust factor at play. An employee who successfully downloads their payslip from the portal on the first try is far more likely to use the same portal for a leave request later. An employee whose first experience with the portal is a failed or confusing leave submission is likely to go straight back to WhatsApp.

How Does This Reduce HR’s Daily Workload Without New Spend?

Once ESS handles routine requests, HR’s daily volume of WhatsApp messages drops to genuine exceptions — a system error, a lost password, an urgent leave case. The requests that remain are the ones that actually need a human, instead of every request needing one.

This shift also changes what an HR operations role actually looks like day to day. Instead of the morning being consumed by a backlog of overnight messages, HR can spend that time on tasks that genuinely need judgment — a policy exception, an escalated dispute, onboarding for a new hire — rather than re-answering the same payslip question for the fifth time that week.

What Should an Employee Self-Service Module Actually Include?

1. Leave application and balance tracking — employees apply and check status without messaging HR

2. On-demand payslip download — available the moment payroll is processed, no request needed

3. Document requests — offer letters, experience letters, and Form 16 available through the same portal

4. Push notifications — leave approvals and payslip availability sent directly, replacing the need to ask

5. Manager approval workflows — leave requests route automatically to the right approver, with no manual follow-up

A module that only covers payslips but not leave, or only leave but not documents, tends to leave a gap that WhatsApp quietly fills back in. The goal isn’t to reduce WhatsApp usage for one request type — it’s to remove HR as the default channel for every routine request an employee might have.

Does This Actually Save Money, or Just Shift the Work?

If ESS is already part of the existing HRMS licence, the cost is zero — the feature exists, it’s simply unused. Even where a company needs to add ESS as a module, the ongoing cost is typically lower than the HR hours currently spent manually answering repeat requests every single day.

The more relevant comparison isn’t software cost against zero — it’s software cost against the hidden cost of HR time already being spent on requests that don’t need a person to handle them. For most companies, that trade works out in favour of activating or adding ESS, even before accounting for the reduced dispute risk from having a proper audit trail.

What Should HR Watch Out for During the Transition?

1. Employees without smartphone access — a small number of employees, especially in field or factory roles, may need an alternative like an SMS-based or kiosk option

2. Data accuracy before go-live — leave balances and employee records need to be correct in the system before employees start relying on it, or the first bad experience will undo the transition

3. Manager buy-in — if managers keep approving leave over WhatsApp instead of through the app, the whole shift stalls regardless of what employees do

This isn’t a topic covered in isolation — the same underlying issue of scattered, unsynced HR data shows up across version control and payroll mismatches more broadly. Fixing WhatsApp-based requests is often the first visible symptom of a company outgrowing its manual or semi-manual HR processes.

References

[1] Payment of Wages Act, 1936, Section 13A – record-keeping requirements for employee wage data: clc.gov.in
[2] Capterra’s 2025 HR Software Trends Survey — tool usage and adoption patterns among HR professionals: capterra.com


TalentCo HR Services LLP is an HR consulting and solutions company offering services across HR operations, compliance, liasoning, payroll management, and HR technology through its proprietary platform ABStart. This article is intended for general informational and educational purposes only. Processes and features may vary by HRMS provider. Readers are advised to verify current capabilities with their specific HR software vendor before making implementation decisions.

What Are the Exact Statutory Thresholds Where an Indian SME Must Transition From Manual HR to an HRMS?

At What Headcount Does Manual HR Legally Stop Being an Option?

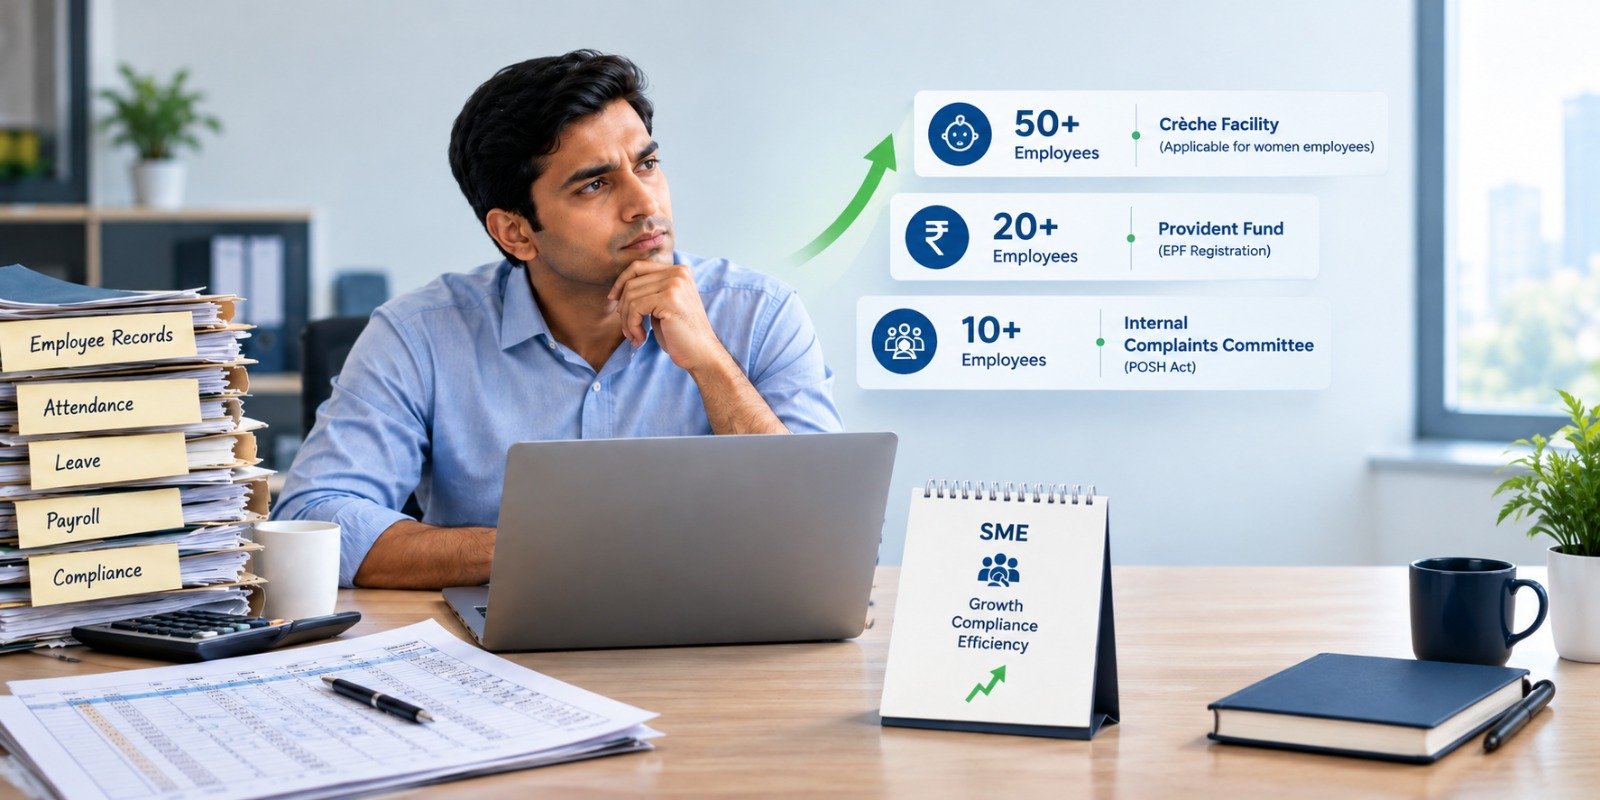
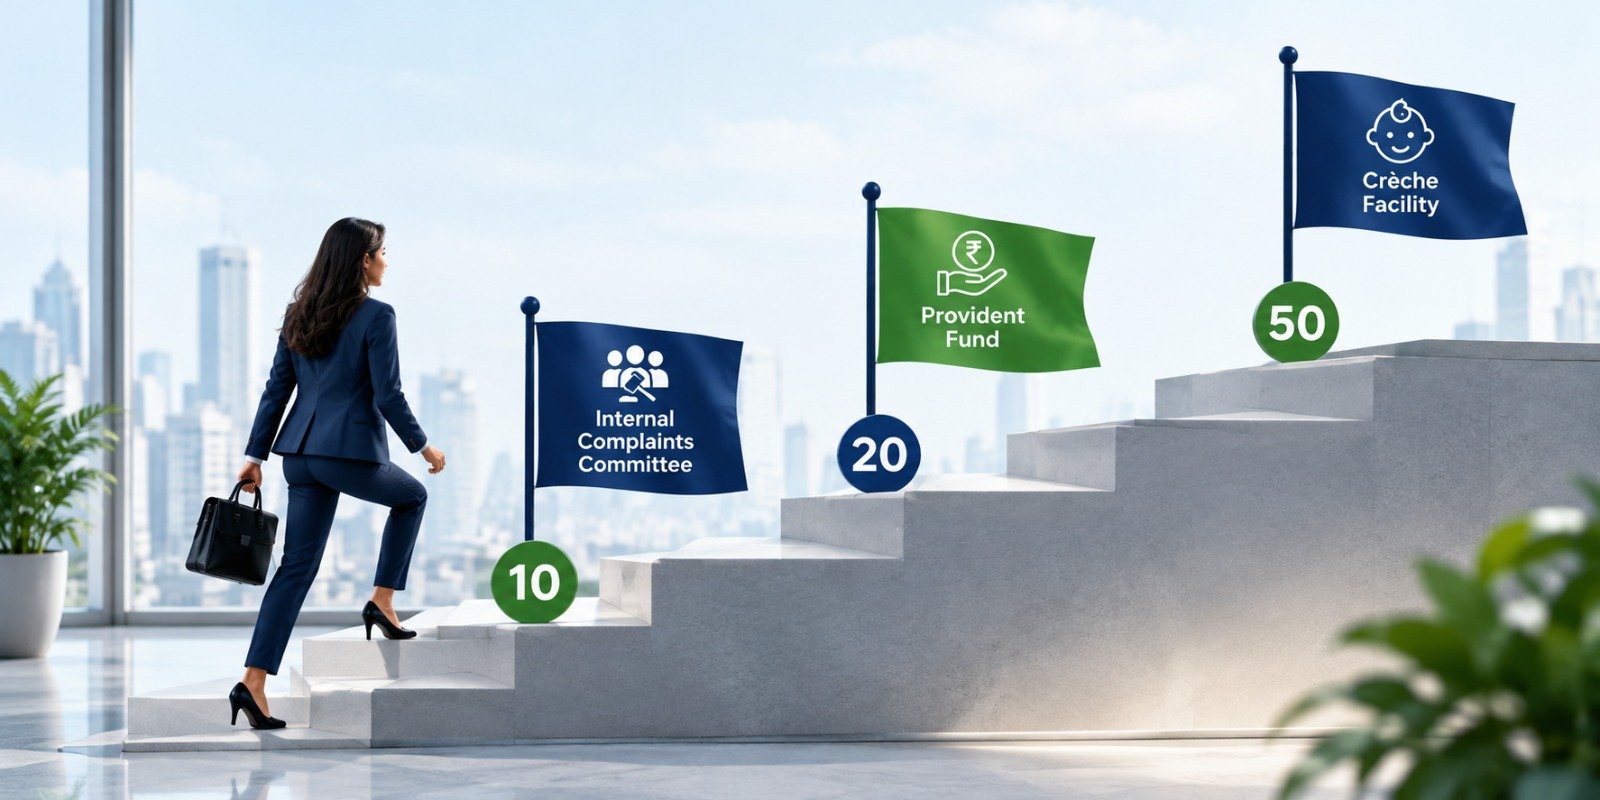
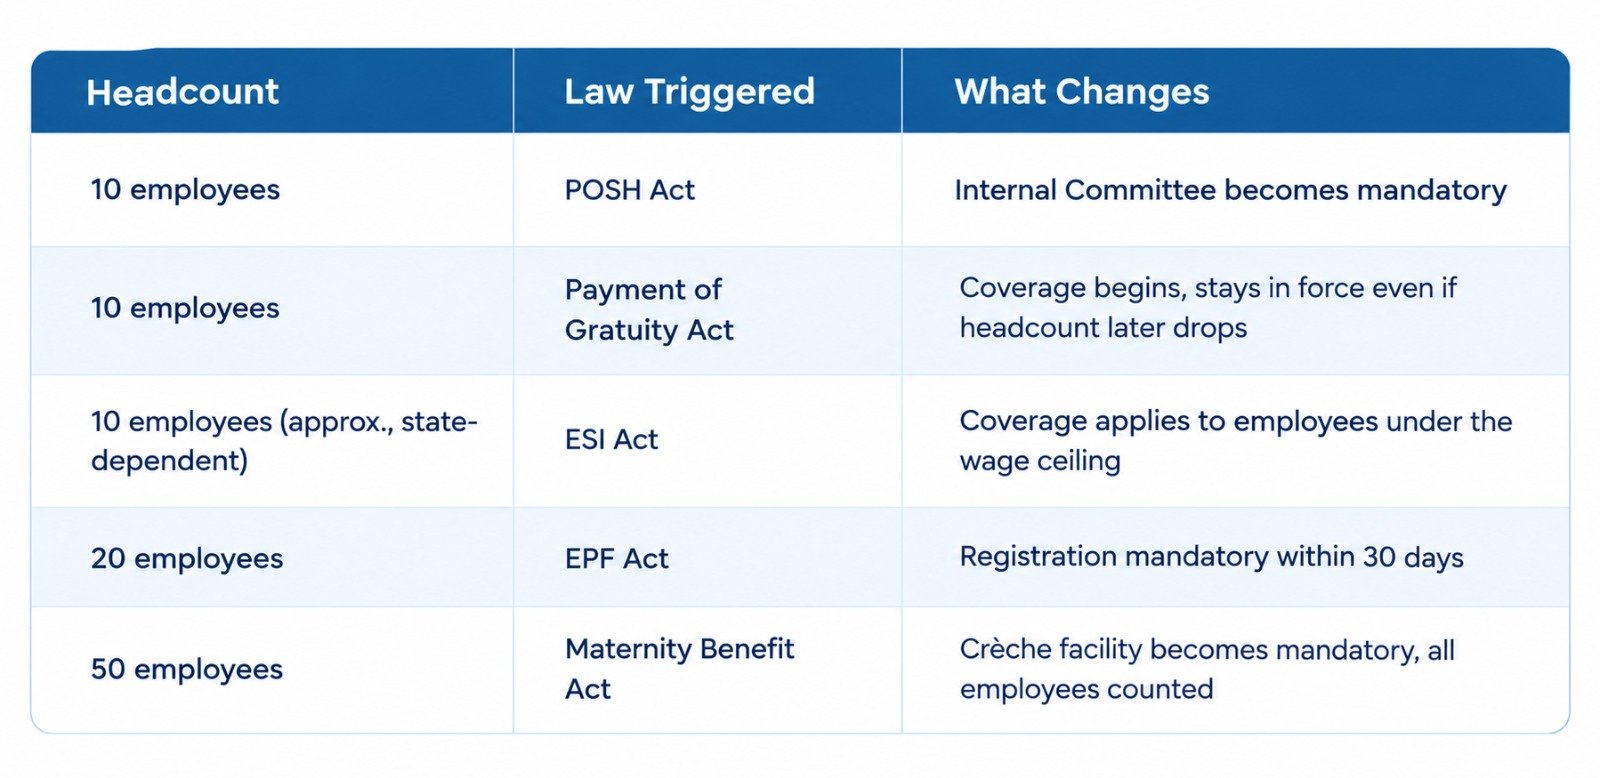
Three headcounts change everything: 10, 20, and 50 employees. Each one activates a different law with its own compliance obligation. Below 10, most statutory requirements don’t apply. Past 50, the number of obligations running in parallel makes manual tracking practically unsustainable, not just legally risky.

Most founders treat these numbers as background facts they’ll deal with “when it comes up.” In practice, each threshold arrives quietly, tied to a specific date rather than a gradual ramp, and by the time it’s noticed, the obligation has usually already been active for weeks or months.

What Are the Exact Thresholds and the Laws They Trigger?

All thresholds count contract staff, interns, and trainees, not just full-time payroll — and most are triggered by crossing the number on any single day, not by an average headcount over the year. This single detail causes more missed thresholds than any other, because internal headcount trackers usually reflect only people on the official payroll register, not the full working population of the establishment on a given day.

To see how unorganised master files trigger these audit risks, read our detailed guide on spreadsheet HR operational risks.

How Does the POSH Internal Committee Requirement Actually Work at 10 Employees?

The moment total headcount touches 10, the POSH Act requires a formally constituted Internal Committee: a senior woman as presiding officer, at least two internal members, and one external member from outside the organisation. Below 10 employees, complaints instead route to a government-appointed Local Committee.

Constituting the committee is only the first step. It needs a documented complaint process, defined inquiry timelines, and an annual report filed with the district officer. A company that forms the committee but never documents how a complaint would actually be handled hasn’t fully met the requirement — it has met the letter of it, but not the operational substance.

Why Does Gratuity Coverage Also Begin at 10 Employees, and Why Does It Matter So Early?

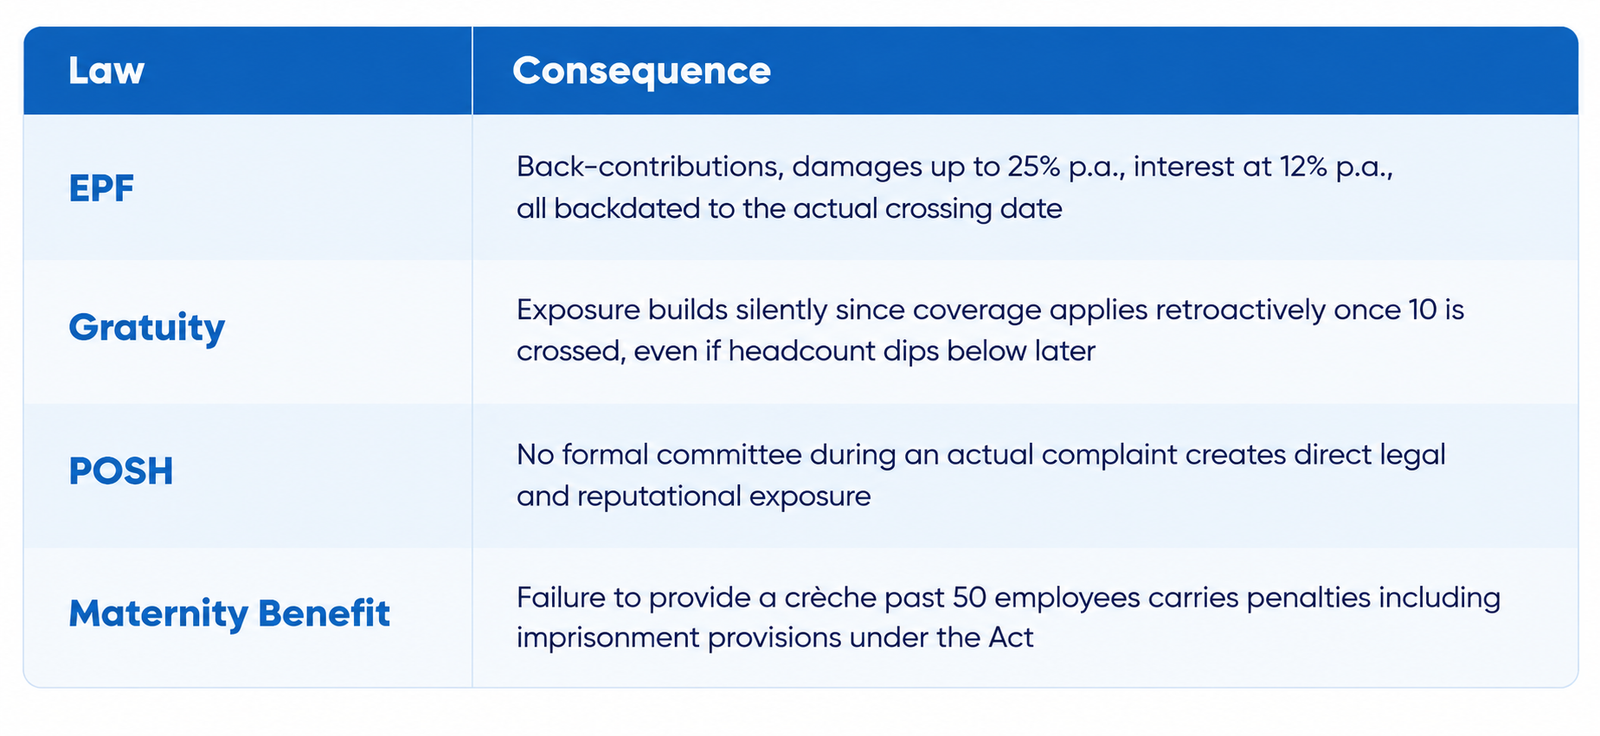
The Payment of Gratuity Act applies once an establishment employs 10 or more people on any day in the preceding 12 months, covering shops, factories, and most other establishment types. Once triggered, this coverage is permanent — it continues even if headcount later drops below 10.

Gratuity is easy to overlook early because the actual payout obligation only arises after five years of continuous service. But the coverage decision is made much earlier, at the point of crossing 10 employees, and companies that don’t track that crossing date accurately can later struggle to determine exactly which employees are covered and from when — a problem that only surfaces years later, at the point of someone’s exit.

How Does ESI Coverage Differ From the Other Thresholds?

ESI typically applies once an establishment crosses 10 employees, covering anyone earning up to a specified wage ceiling for medical and cash benefits. Unlike POSH or gratuity, this isn’t a one-time trigger — eligibility depends on wage bands that shift with every salary revision, and the exact threshold can vary somewhat by state.

An employee under the wage ceiling today can move out of ESI coverage after a routine increment, and a new hire brought in below the threshold enters coverage immediately. A system that only reviews headcount once a year, during annual appraisals, will systematically miss these mid-year shifts — which means ESI contribution filings can be out of sync with actual coverage status for months without anyone noticing.

Why Is 20 Employees the Threshold With the Most Expensive Consequences?

Cross 20 employees — on any single day, counting part-time and contract staff — and EPF registration becomes mandatory within 30 days. Miss the window, and the penalty isn’t calculated from the date of discovery. It’s backdated to the actual date headcount crossed 20: back-contributions, damages of up to 25% per annum under Section 14B, and interest of 12% per annum under Section 7Q. Coverage, once triggered, doesn’t reverse even if headcount later falls below 20.

This threshold is particularly easy to cross without noticing because EPF applicability is assessed per establishment, counted on any single day, rather than as an annual average. A short-term spike in contract or seasonal hiring — a festive season push, a project ramp-up — can trigger the 20-employee threshold for a brief period, and if nobody records that specific date, the company has no internal record of exactly when its obligation began.


“Most SMEs don’t miss these thresholds because they’re careless — they miss them because nobody’s job is to watch the headcount number every single day. By the time an inspector asks for proof, the company is defending a gap it didn’t even know existed.”

— Rahul Dhamdhere
Founder & Managing Director, ABStart HRMS

What Changes Once a Company Crosses 50 Employees?

At 50 employees, the Maternity Benefit Act requires every establishment to provide a crèche facility within a prescribed distance of the workplace, typically within 500 metres under most state guidelines, with women employees permitted four visits per day. This threshold counts all employees, not just women, which surprises many SMEs that assume the obligation only applies once they cross 50 female employees specifically.

By this stage, a company is usually also fully covered under EPF, ESI, gratuity, and POSH, which means 50 employees marks the point where every major HR-related statutory obligation is active simultaneously. This is also typically where the volume of routine compliance activity — filings, registers, renewals — makes a manual or semi-manual system genuinely difficult to sustain, independent of any single mistake.

What Happens If an SME Crosses These Thresholds Without Noticing?

What makes these consequences harder to manage in practice is that they rarely surface in isolation. An inspection triggered by one issue — an unrelated complaint, a routine audit — often uncovers gaps across several thresholds at once, because the same underlying problem (no reliable headcount tracking) tends to affect every threshold equally.

Labor inspections in India occur via both Shram Suvidha portal digital audits and on-site physical visits by Labour Officers/Enforcement Officers (triggered by employee complaints or randomized portal selection)

Why Do These Thresholds Cluster Precisely in the 20–100 Employee Range?

This is exactly where most Indian SMEs are scaling fastest and formalising slowest. A company hiring aggressively can cross 10, 20, and edge toward 50 within the same calendar year — meaning three separate legal obligations can activate in quick succession, often before HR headcount, process maturity, or dedicated compliance ownership has caught up with the pace of hiring.

Below 20 employees, the operational cost of a missed threshold is usually contained — fewer people affected, easier to correct manually. Past 100, most companies have already been forced into a formal HR function simply because the volume of activity leaves no other option. The 20–100 range is where the gap between legal obligation and operational readiness is widest, and where the cost of that gap is highest.

What Should an HRMS Actually Track at Each of These Thresholds?

1. Live headcount monitoring— flags the exact date of crossing 10, 20, and 50 employees

2. Wage-band tracking— flags ESI eligibility shifts automatically with every salary revision

3. Committee and compliance documentation— stores POSH Internal Committee records and annual filings in one place

4. Crèche and benefit tracking— flags Maternity Benefit obligations once headcount crosses 50

5. Audit-ready history— every threshold crossing timestamped and exportable on demand

A structured system doesn’t change the underlying legal obligations — each of these laws applies exactly as written, regardless of what tools a company uses. What it changes is whether the company can prove, with a timestamped record, exactly when each obligation began.

How Should a Growing SME Actually Approach This Transition?

1. Establish the current headcount precisely, including contract, part-time, and trainee staff, as a documented baseline

2. Check that baseline against each threshold — 10, 20, and 50 — to confirm which obligations already apply

3. Consolidate all employee records into one editable, access-controlled file rather than several parallel spreadsheets

4. Set a recurring review of headcount and wage bands against each threshold, rather than relying on someone happening to notice

5. Move to a system that automates this tracking once the current data is confirmed accurate

Skipping the first two steps is the most common mistake. Some companies move straight to purchasing software without first confirming whether they’ve already crossed a threshold — which means the new system simply inherits the same blind spot it was meant to solve.

References

[1] Employees’ Provident Fund Organisation (EPFO) – EPF Act, 1952, Section 14B, Section 7Q: epfindia.gov.in
[2] Sexual Harassment of Women at Workplace (Prevention, Prohibition and Redressal) Act, 2013, Section 4: government notification
[3] ESIC – Employees’ State Insurance Corporation Official Portal: esic.gov.in
[4] Payment of Gratuity Act, 1972 – Chief Labour Commissioner: clc.gov.in
[5] Maternity Benefit (Amendment) Act, 2017, Section 11A – Ministry of Labour and Employment: labour.gov.in


TalentCo HR Services LLP is an HR consulting and solutions company offering services across HR operations, compliance, liasoning, payroll management, and HR technology through its proprietary platform ABStart. This article is intended for general informational and educational purposes only. Labour laws and compliance thresholds are subject to change and can vary by state. Readers are advised to independently verify current regulations or consult qualified professionals before making any business decisions.

At What Headcount Does Managing Employee Records on Spreadsheets Become a Legal and Operational Risk for Indian SMEs?

Why Does Spreadsheet-Based HR Actually Break Down as a Company Grows?

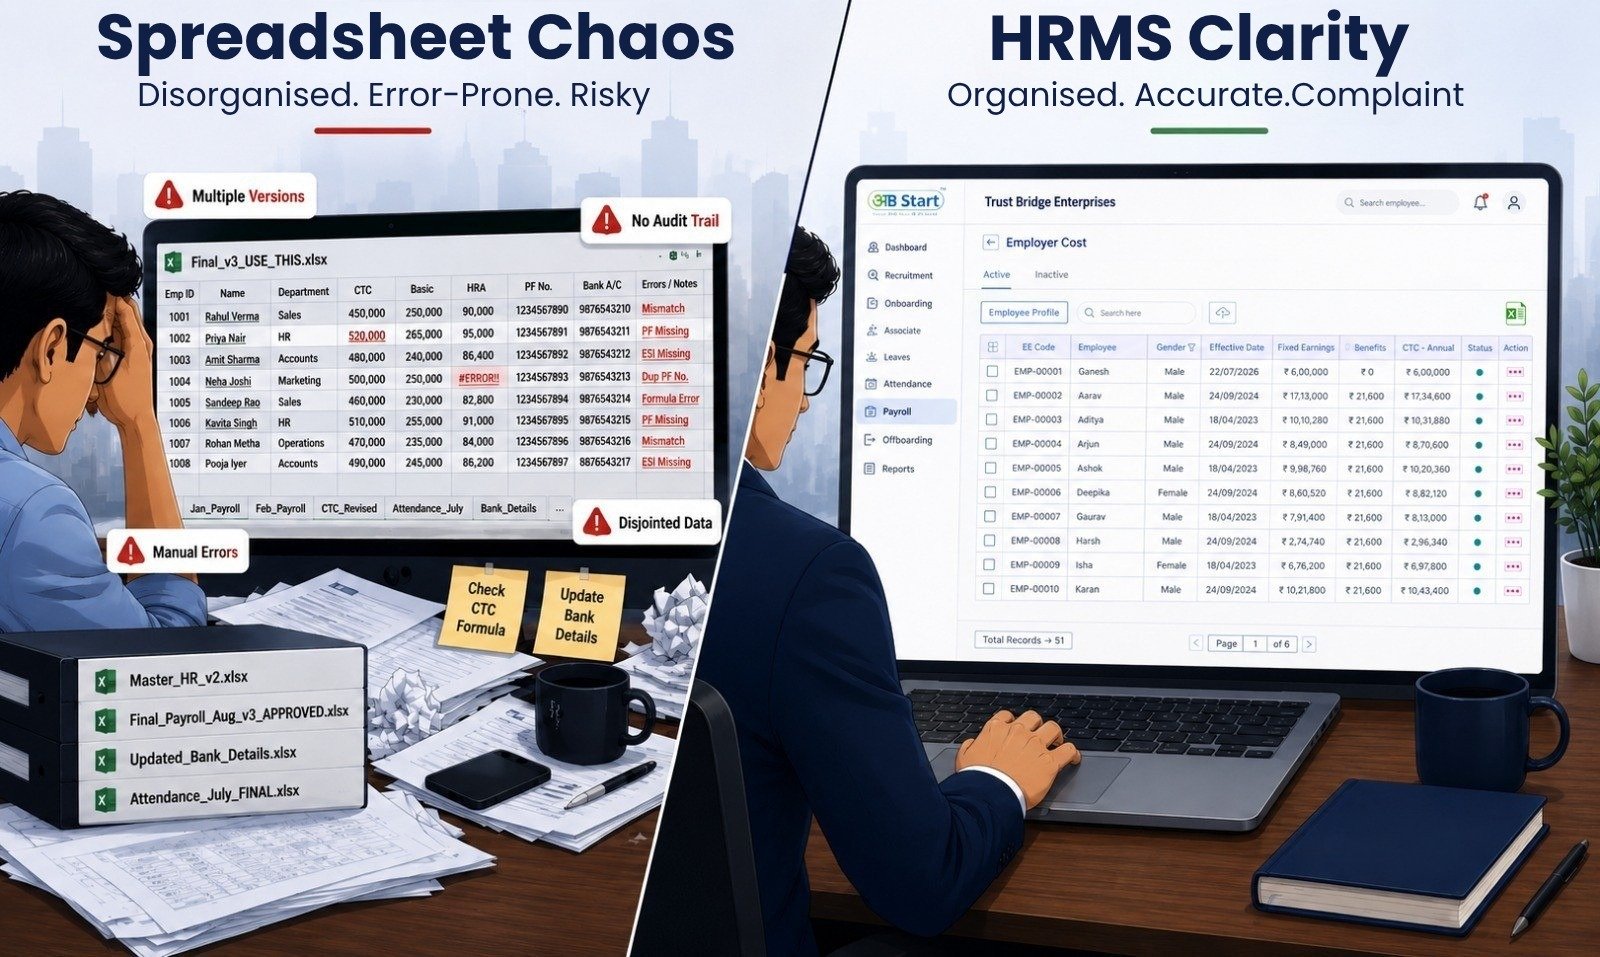
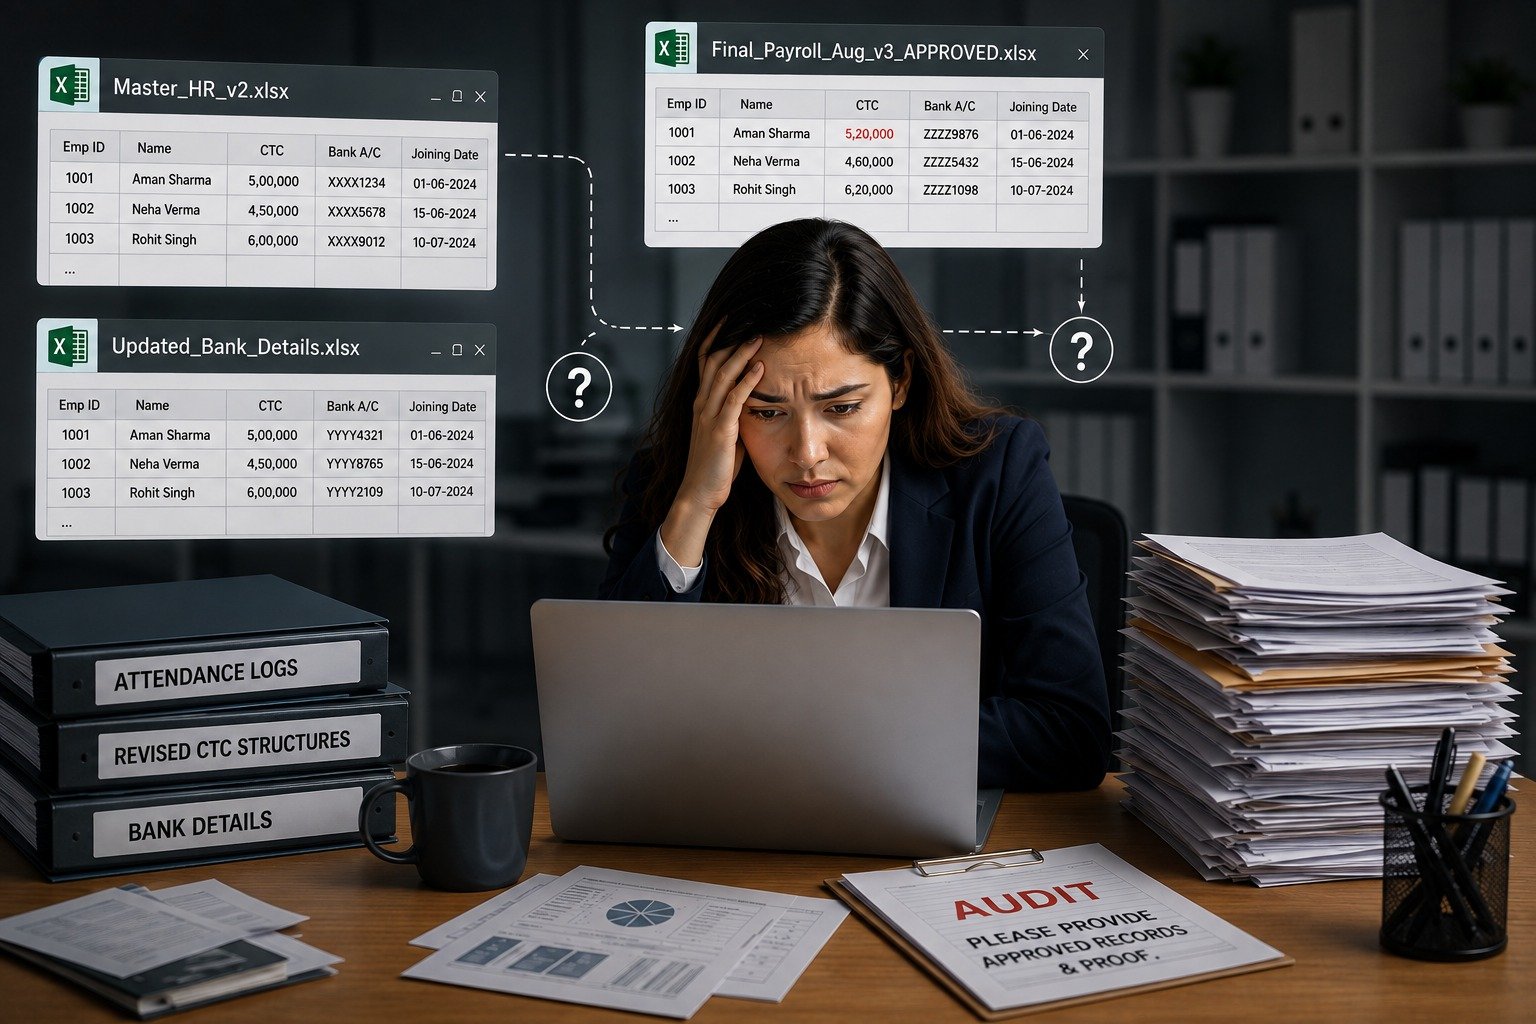
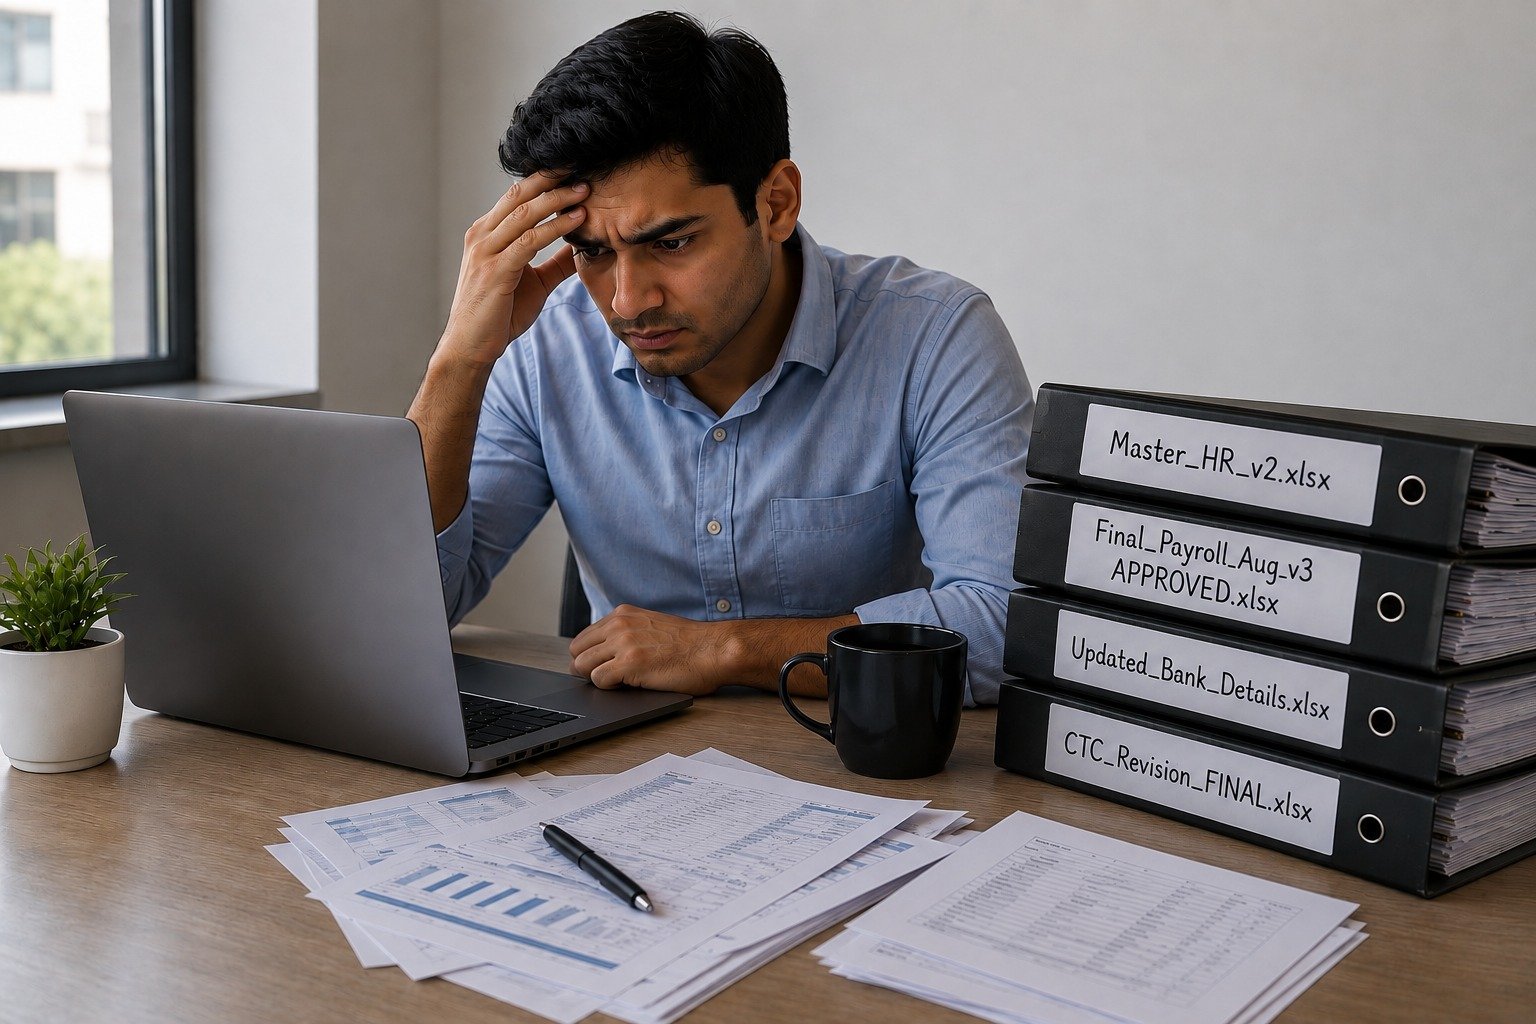
Managing 30+ employees on spreadsheets rarely fails because HR doesn’t know how to use Excel. It fails because four “final” versions of the same file end up on four different laptops. When attendance logs, revised CTC structures, and bank details live in disconnected sheets, nobody knows which record is approved until payroll miscalculates or an auditor asks for proof.

The legal exposure EPF, ESI, and other statutory obligations  is usually a downstream consequence of this disorganisation, not the root cause. Fix the data structure, and the compliance risk shrinks with it.

What Does Version Control Chaos Actually Look Like Inside an SME?

Version control chaos is the most common failure point. Multiple conflicting files circulate across local desktops, Google Sheets, and email attachments, and no one can confirm which one is current:

1. Master_HR_v2.xlsx

2. Final_Payroll_Aug_v3_APPROVED.xlsx

3. Update_Bank_Details.xlsx

Each file gets edited independently. By the time payroll runs, two or three of these versions may already disagree on the same employee’s salary or bank account, and nobody can say with certainty which edit came last.

Why Does the Lack of an Audit Trail Create Real Risk?

Spreadsheets allow silent edits to salary figures, bank account numbers, or joining dates, with no timestamped approval history. When an internal audit or labour inspection occurs, management cannot prove which sheet was the actual “final approved version.”

This isn’t a hypothetical risk  it’s the exact gap that turns a routine audit into a drawn-out dispute. An inspector or auditor doesn’t just want the current numbers; they want proof of who approved a change and when. A spreadsheet has no built-in way to provide that.

“When an auditor steps into an SME, they aren’t looking for malicious intent; they are looking for single-source proof. If HR cannot produce a timestamped, tamper-proof history of salary revisions and attendance logs, the company is forced into a defensive position regardless of how honest their payroll practices were.”

— Shailendra Dhamdere, Founder & Managing Director, ABStart HRMS

Why Do Multiple Departments Working Off Different Sheets Cause Problems?

Data generated in attendance logs, recruitment trackers, field apps, and finance records routinely fails to sync into one central master sheet. Each department maintains its own version of the truth, and reconciling them becomes a manual, error-prone task every payroll cycle.

This multi-source disconnect compounds over time. A new hire entered correctly in the recruitment tracker may never make it into the attendance system in the same format, and a mid-year salary revision logged in finance may not reach the master HR sheet for weeks. Every disconnect adds another point where numbers can quietly diverge.

What Actually Happens During an Audit When Records Are Scattered?

The exposure becomes concrete the moment an inspector asks for historical wage registers. If HR can only produce conflicting, unverified Excel exports pulled from different desktops, there is no single document to point to as the official record  and that gap itself becomes the finding.

At that point, the conversation shifts from “are you compliant” to “can you prove it,” which is a much harder position to defend, regardless of whether the company was actually following the rules in practice.

Where Does Statutory Compliance Fit Into This Picture?

Once master data is disorganised, statutory risk follows naturally. A few thresholds to be aware of:

1.EPF — mandatory once headcount crosses 20 on any single day, with penalties backdated to the actual crossing date if registration is missed

2.ESI — typically applies once headcount crosses 10, with coverage tied to wage bands that shift with every salary revision

3.POSH — an Internal Committee becomes mandatory at 10 employees, as part of general statutory awareness alongside EPF and ESI

Each of these depends on having a reliable, current headcount and wage record. Without that, even a company aware of the rules can miss the exact date an obligation began.

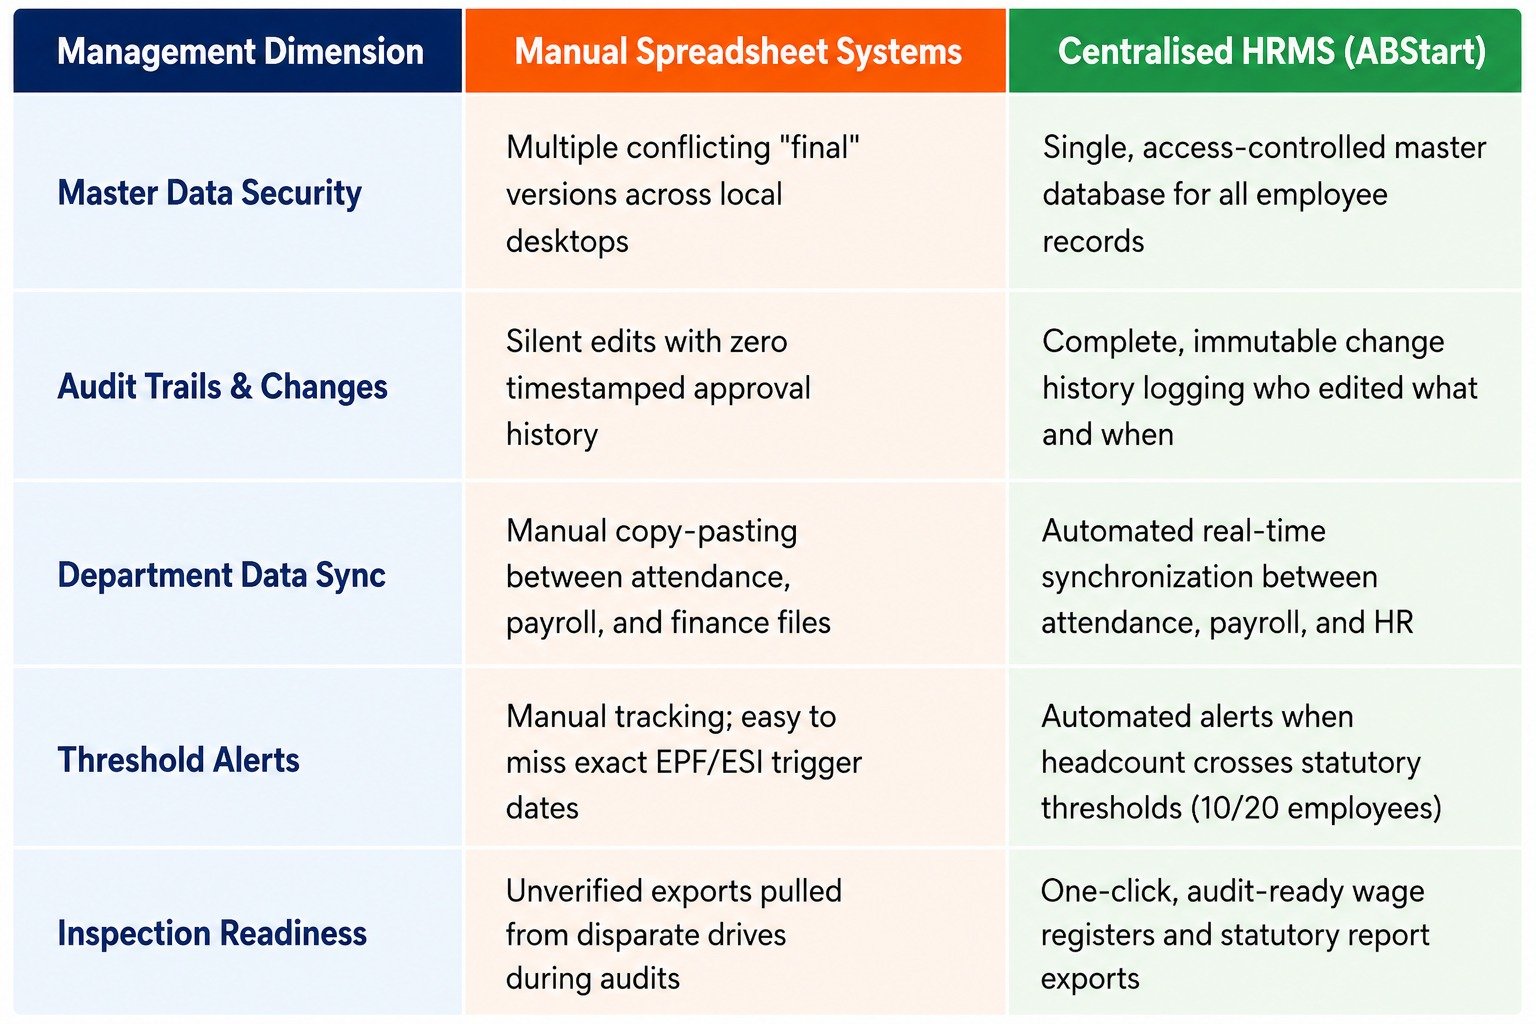
Comparing Spreadsheets vs. Centralized HRMS

To understand how moving away from manual files protects growing SMEs, compare the operational differences across key management dimensions:

Why Is the 20–75 Employee Band the Riskiest Stage for This Kind of Failure?

Below 20 employees, a data error is usually contained to one or two people and cheap to fix by hand. Past 75, most companies have already been forced into a proper HR function by sheer operational necessity. The 20–75 band sits in between: large enough that one bad sheet touches dozens of records, small enough that leadership still assumes “we’ll formalise this later.”

Get a Free Custom Demo of ABStart HRMS→https://talentcohr.com/abstart/


What Does a Single Source of Truth Actually Fix?

1.One master record per employee — replaces the multiple “final” file problem entirely

2.Timestamped change history — every edit to salary, bank details, or joining date is logged with who made it and when

3.Automatic department sync — attendance, recruitment, and payroll data update the same record instead of separate sheets

4.Audit-ready exports — wage registers and historical records available in one verified format on demand

5.Threshold tracking — flags the exact date headcount crosses 10 or 20, so EPF, ESI, and POSH obligations are caught on time

References

[1] Employees’ Provident Fund Organisation (EPFO) – EPF Act, 1952, Section 14B, Section 7Q: epfindia.gov.in
[2] Sexual Harassment of Women at Workplace (Prevention, Prohibition and Redressal) Act, 2013, Section 4: government notification
[3] ESIC – Employees’ State Insurance Corporation Official Portal: esic.gov.in
[4] Code on Social Security, 2020 – Ministry of Labour and Employment: labour.gov.in


TalentCo HR Services LLP is an HR consulting and solutions company offering services across HR operations, compliance, liasoning, payroll management, and HR technology through its proprietary platform ABStart. This article is intended for general informational and educational purposes only. Labour laws and compliance thresholds are subject to change and can vary by state. Readers are advised to independently verify current regulations or consult qualified professionals before making any business decisions.

NPS New Withdrawal Rules 2026: 80:20 Split, ₹8L Slab & More Explained

NPS New Withdrawal Rules 2026: What Actually Changed, and Who It Applies To?

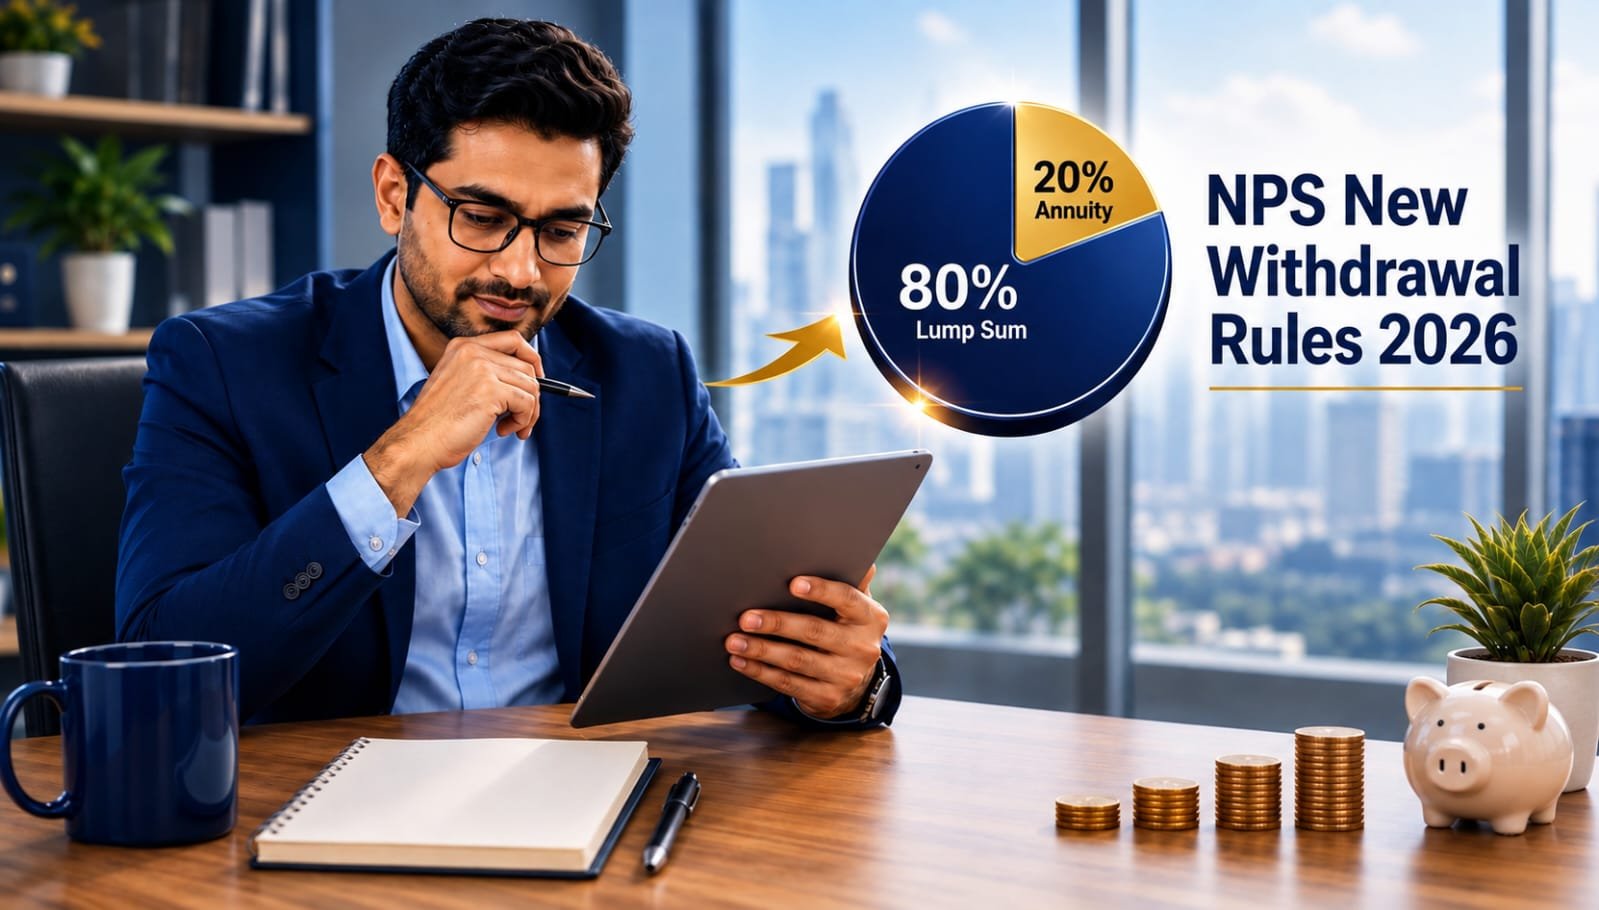
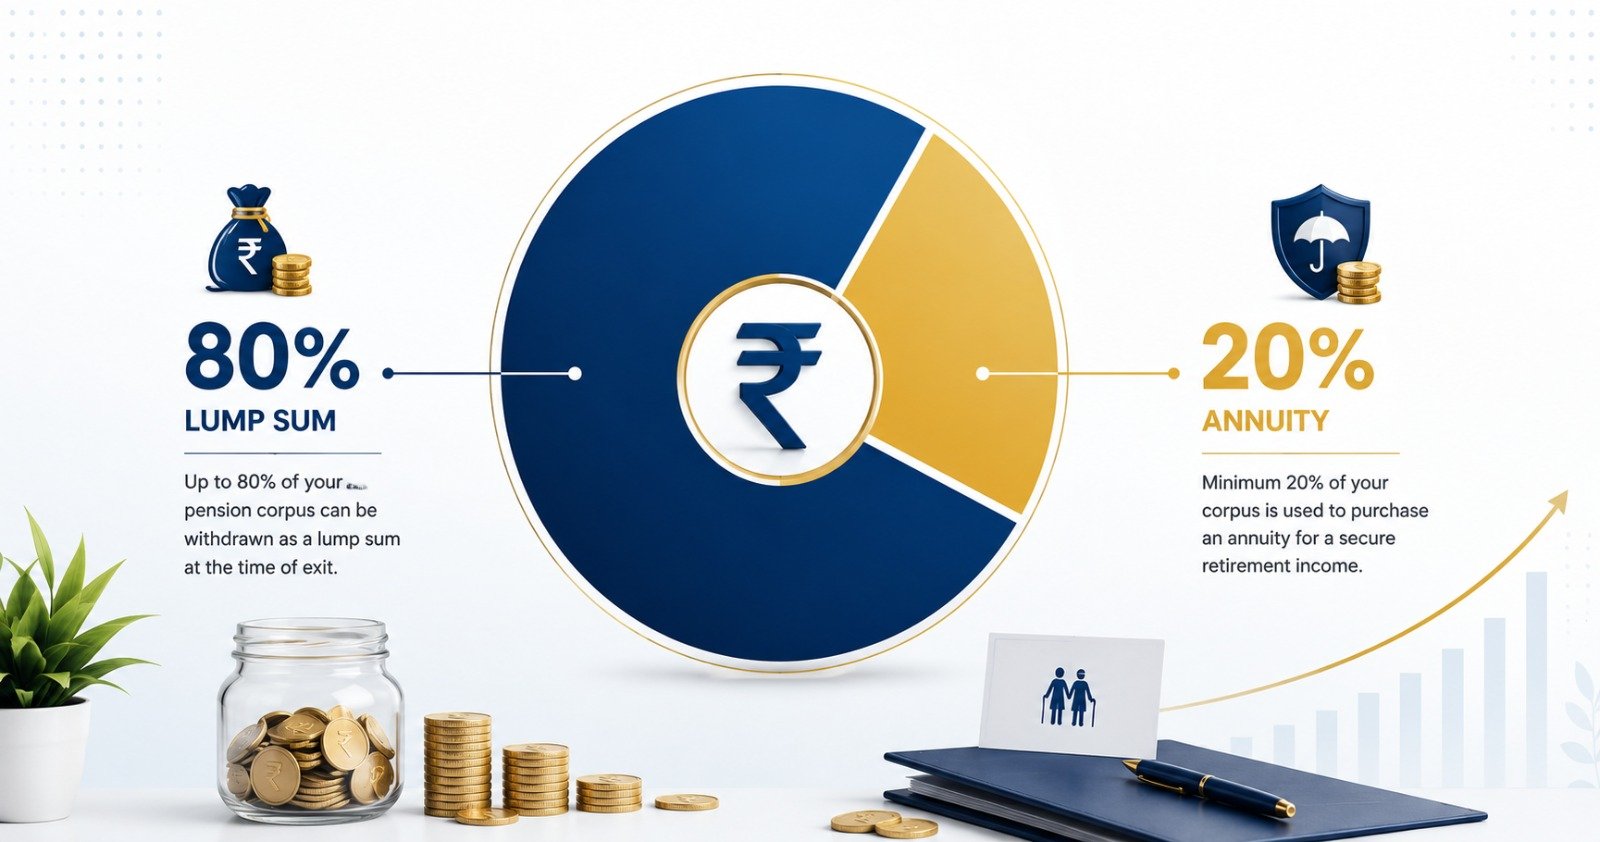
1. Non-government NPS subscribers (Corporate NPS & All Citizen Model) can now withdraw up to 80% as lump sumat normal exit, up from 60% — annuity requirement drops to a minimum of 20%.

2. Government employees are unaffected and stay on the older 60:40 splitfor corpus above ₹12 lakh.

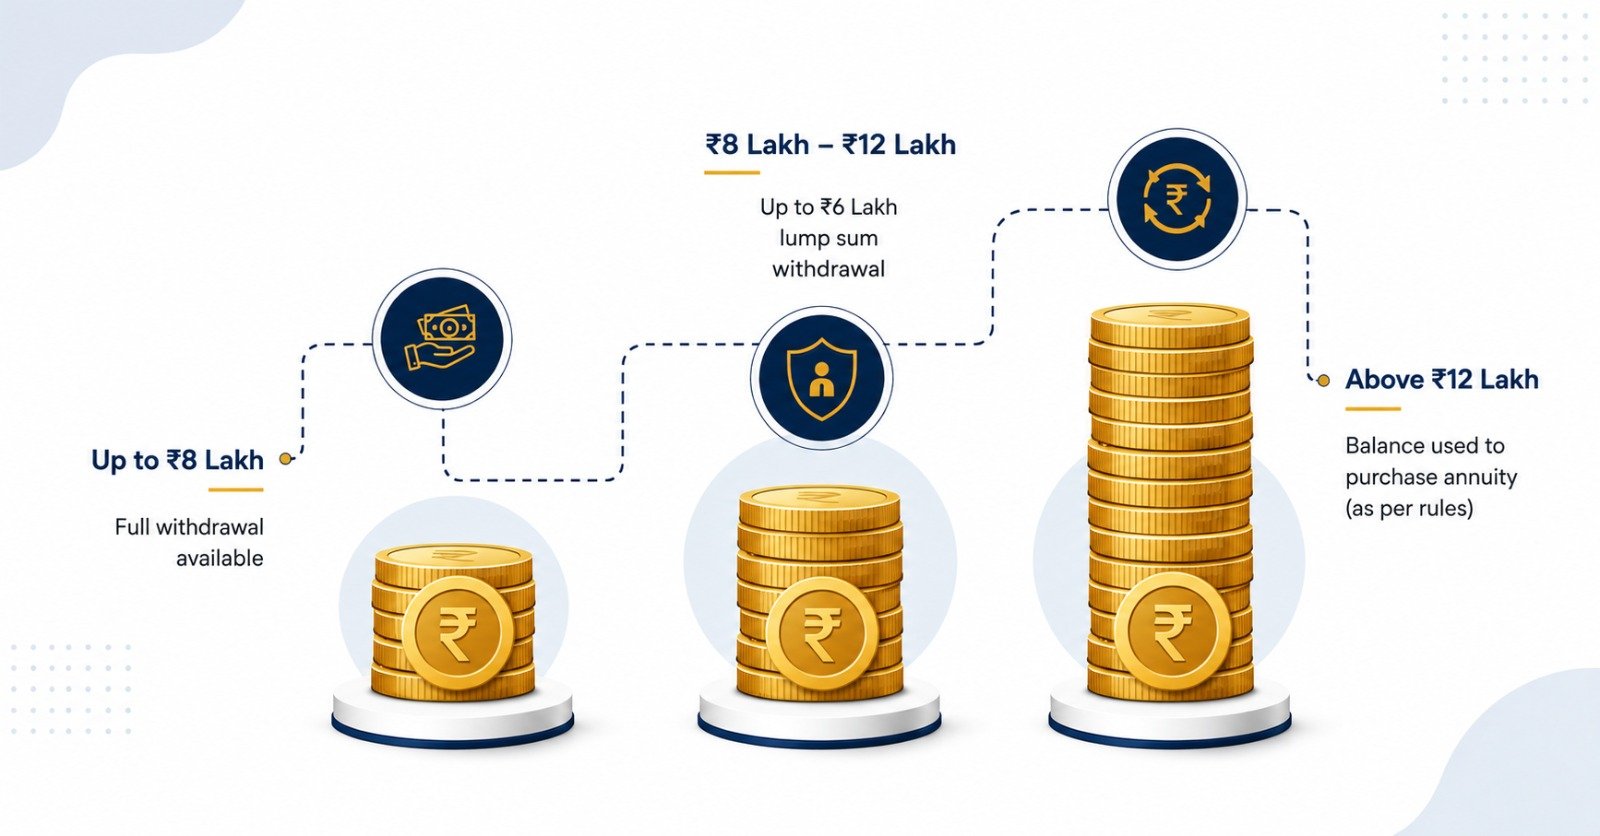
3. Corpus ≤ ₹8 lakhat normal exit → full withdrawal, no annuity needed; between ₹8L–₹12L → up to ₹6 lakh as lump sum.

4. Premature exit with corpus ≤ ₹2.5 lakhcan be withdrawn in full; above that, 80% still goes into annuity.

5. Tax exemption on the lump sum stays capped at 60% of the corpus under Section 10(12A)— the rules don’t change how withdrawals are taxed.

6. Rules came via the PFRDA (Exits and Withdrawals under NPS) (Amendment) Regulations, 2025, notified in December 2025— not a fresh 2026 regulation.

If you’re a non-government NPS subscriber, you can now pull out up to 80% of your pension corpus as a lump sum. That’s up from 60% earlier — annuity purchase drops to a minimum of 20%. Government employees don’t get this; they’re still on the older 60:40 split. And the rule itself isn’t new-new — it comes from the PFRDA (Exits and Withdrawals under the National Pension System) (Amendment) Regulations, 2025, notified back in December 2025, not some separate 2026 regulation as a few recent write-ups seem to suggest.

Here’s the thing about most NPS content floating around right now: it glosses over exactly who these changes apply to. Government versus non-government, normal exit versus premature exit — mix those up and the whole explanation falls apart. So let’s go through it properly, one piece at a time.

Who does the 80:20 rule actually cover?

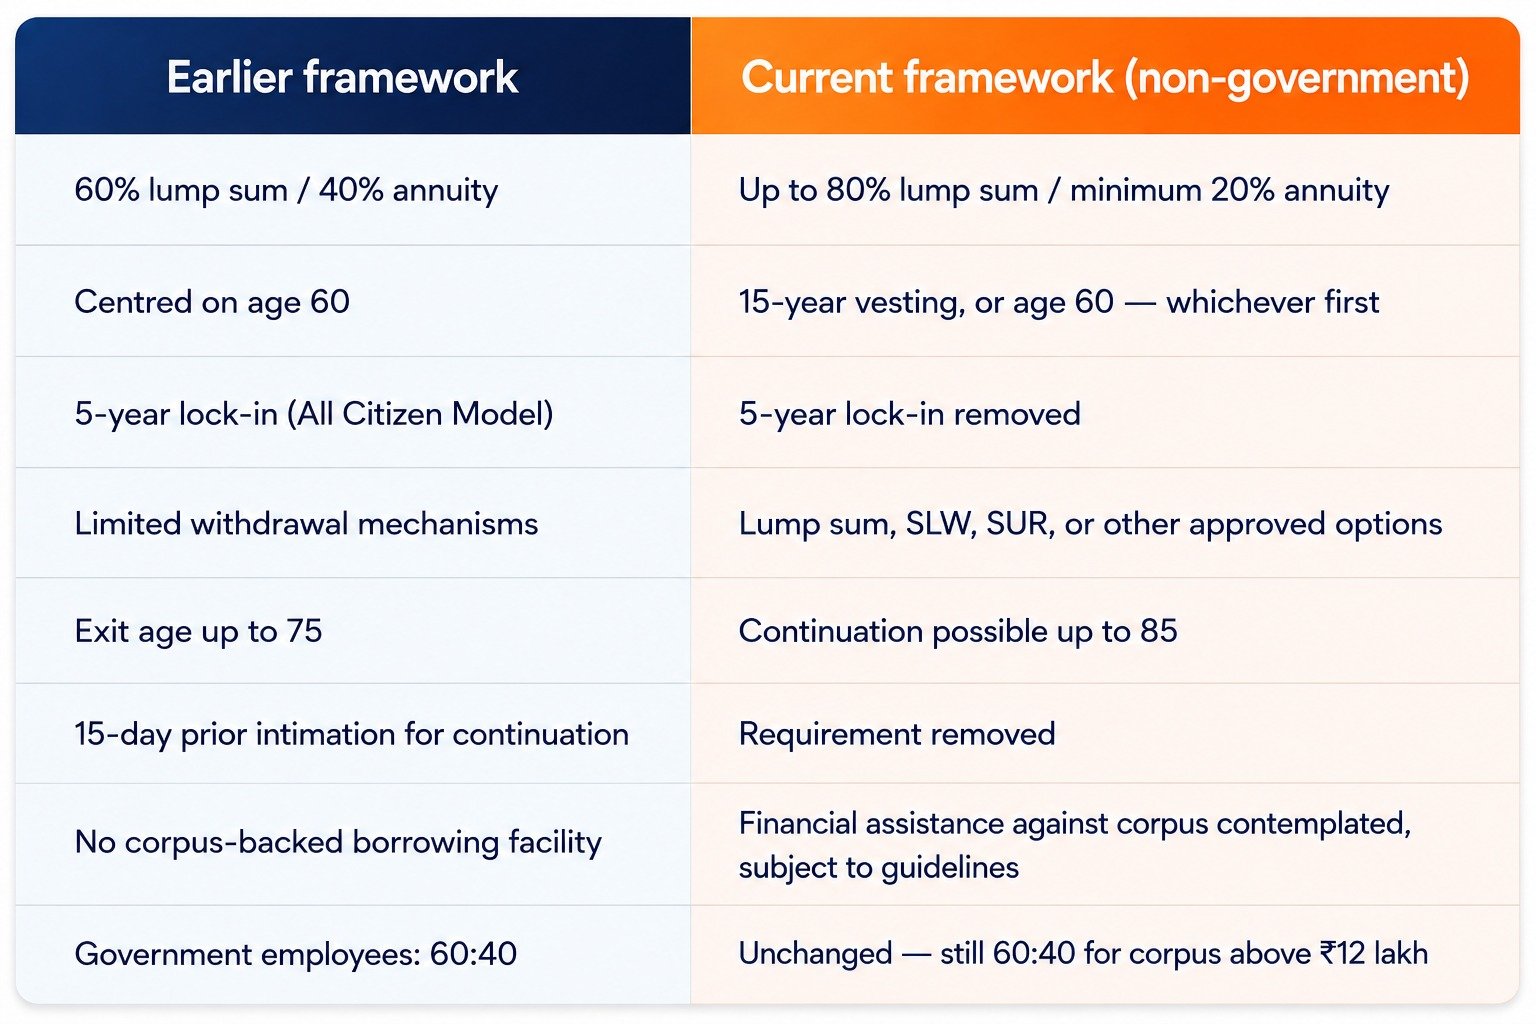
Just non-government subscribers — that’s Corporate NPS and the All Citizen Model. At normal exit (15 years of subscription or age 60, whichever hits first), these subscribers can now take up to 80% as lump sum, with only 20% mandatorily going into annuity. Compare that to the old 60/40 split, and it’s a big jump.

Government employees aren’t part of this change at all. They stay on 60:40 — up to 60% lump sum, at least 40% annuity — for any corpus above ₹12 lakh at superannuation. This is probably the single most common mistake in articles covering this topic: applying the 80:20 figure across the board when it simply doesn’t apply to government subscribers.

Is the 80% still paid out as one lump sum?

Not necessarily, and this part often gets missed. The regulations don’t just widen the lump-sum percentage — they also open up how you actually receive it. Along with a straight lump sum, subscribers can now choose Systematic Lump Sum Withdrawal (SLW) or Systematic Unit Redemption (SUR). So instead of everything landing in your account on day one, you can space it out. It’s less “retire, withdraw everything, buy an annuity” and more a proper retirement-income structure where you decide the pace.

What’s changed about the vesting period and lock-in?

Under the All Citizen Model, normal exit now kicks in after 15 years of subscription, or age 60 — whichever comes first. Earlier, this was tied almost entirely to turning 60. So someone who’s put in 15 years can qualify for normal-exit benefits well before they hit 60, depending on the scheme’s specific conditions.

Separately — and this trips people up — the 5-year lock-in for premature exit under the All Citizen Model has been dropped. Worth being careful here: lock-in and vesting aren’t the same thing. Removing the lock-in doesn’t mean you can walk away with the whole corpus whenever you like. Premature exit, normal exit, and partial withdrawal each still run on their own separate rules.

Does having a smaller corpus get you anything extra?

Yes, and the thresholds have moved up quite a bit. The rules work off two separate benchmarks depending on whether it’s a normal exit or a premature exit:

1. Normal exit, corpus ≤ ₹8 lakh: full withdrawal allowed — lump sum, SLW, or SUR — with no annuity requirement at all.

2. Normal exit, corpus between ₹8 lakh and ₹12 lakh: up to ₹6 lakh as lump sum, with the rest handled through systematic withdrawal or annuity.

3. Premature exit, corpus ≤ ₹2.5 lakh: full withdrawal allowed, no annuity needed.

4. Premature exit, corpus above ₹2.5 lakh: standard premature-exit rules apply — up to 20% lump sum, minimum 80% annuity.

Two thresholds, two different situations — ₹8 lakh for normal exit, ₹2.5 lakh for premature exit — and it’s easy to accidentally swap them when writing or reading about this.

What about premature exit specifically?

This is still the stricter of the two. Exit before completing 15 years, or before age 60 — whichever applies earlier under your scheme — and at least 80% of your corpus has to go into annuity, with up to 20% available as lump sum. That ratio hasn’t budged.

The one exception is the small-corpus rule above: ₹2.5 lakh or less at premature exit, and you can take the whole amount, no annuity needed.

Worth keeping the two structures straight:

1. Normal exit: up to 80% lump sum, minimum 20% annuity (non-government)

2. Premature exit: up to 20% lump sum, minimum 80% annuity — unless corpus is ₹2.5 lakh or under, in which case it’s 100% withdrawal

How do partial withdrawals work now?

You can still withdraw without a full exit — up to 25% of your own contributions. Emphasis on own contributions. This is calculated strictly on what you personally put in, not employer contributions, and not the investment growth on top. It’s not 25% of whatever your account is currently worth.

Under the All Citizen Model, subscribers under 60 can make up to four partial withdrawals, spaced at least four years apart. Past 60, the gap eases to a three-year interval, and the 25% cap on own-contribution still holds. Valid reasons include children’s higher education, children’s marriage, buying or building a house, and medical treatment or disability-related expenses — all subject to the applicable conditions.

Can you borrow against your NPS corpus?

There’s now a provision for subscribers to seek financial assistance against their pension corpus, from a regulated financial institution, with a lien of up to 25% of their own contribution. PFRDA has said separate operational guidelines will govern how this actually works. Calling it “NPS now offers loans” is a bit of an overstatement at this stage — it’s financial assistance secured against the corpus, and the fine print on eligibility and mechanics is still being worked out.

Until when can you stay invested?

Subscribers can now remain in NPS up to age 85 — up from 75 earlier — unless an earlier exit is triggered under the applicable rules. Retirement doesn’t force an immediate cash-out anymore. You can defer withdrawal, defer buying an annuity, or just keep contributing well past the traditional retirement age.

PFRDA has also scrapped the 15-day prior-intimation requirement that used to apply before an account could continue past exit eligibility. Put these together and the direction is pretty clear: NPS is moving away from a single forced exit point, toward something more flexible.

What happens to the money if the subscriber dies?

Under the All Citizen Model, the nominee or legal heir gets 100% of the accumulated pension wealth as a lump sum, with SLW, SUR, or annuity available as alternative options depending on the framework. For estate planning purposes, that matters — the corpus doesn’t disappear or get forced into an annuity just because the subscriber passed away before exiting.

So when were these rules actually notified?

This is where a lot of the recent coverage gets sloppy. The regulations were notified as the PFRDA (Exits and Withdrawals under the National Pension System) (Amendment) Regulations, 2025 — in December 2025. Not a separate “2026 regulation” issued later in the year, which some articles seem to imply. If you’re citing a date for this, December 2025 is the one to use.

Does this change how the withdrawal is taxed?

Not on its own. These regulations decide how much you can withdraw and when — they don’t rewrite the Income Tax Act. Right now, the tax exemption on the NPS lump sum still sits at 60% of the corpus under Section 10(12A) for non-government subscribers. Since the withdrawable lump sum has gone up to 80% in many cases, whatever falls above that 60% exempt slice could be taxable, unless the Income-tax Act gets amended to match. It’s a detail that’s easy to skip past — but one that catches people off guard if nobody flags it in advance.

Separately, this doesn’t touch employer-side tax treatment either. Employer contributions to an employee’s NPS account under a Corporate NPS scheme continue to be deductible for the employer and tax-exempt for the employee up to prescribed limits under Section 80CCD(2) — a detail HR and payroll teams structuring Corporate NPS benefits should keep an eye on.

What changed — quick comparison

Structuring Corporate NPS the Right Way

These changes give non-government subscribers — including employees enrolled through Corporate NPS — meaningfully more flexibility at exit. But that flexibility only helps if the underlying scheme, contribution structure, and employee communication are set up correctly in the first place.

TalentCo HR Services helps corporate clients structure compliant Corporate NPS schemes and broader employee benefit frameworks — from scheme design and vendor coordination to keeping payroll and tax treatment aligned with the latest PFRDA and Income Tax rules.

References

PFRDA — Latest NPS Exits & Withdrawals Regulations
www.pfrda.org.in.
PFRDA — Exits & Withdrawals Amendment Regulations, 2026
www.pfrda.org.in/w/pension-fund-regulatory-and-development-authority-exits-and-withdrawals-under-the-national-pension-system-amendment-regulations-2026
PFRDA — Exits & Withdrawals Amendment Regulations, 2025
www.pfrda.org.in/en/web/pfrda/w/regulatory-framework/regulations/pension-fund-regulatory-and-development-authority-exits-and-withdrawals-under-the-national-pension-system-amendment-regulations-2025
PFRDA — Official Regulations
www.pfrda.org.in/regulatory-framework/regulations


TalentCo HR Services LLP is an HR consulting and solutions company offering services across HR operations, compliance, liasoning, payroll management, and HR technology through its proprietary platform ABStart. This article is intended for general informational and educational purposes only. Tax laws and compliance requirements are subject to change based on government notifications. Readers are advised to independently verify current regulations or consult qualified professionals before making any business or financial decisions.

Why frontline workers leave early and what SMEs should fix during onboarding

Early frontline worker attrition typically begins when wage expectations, identity verification, attendance tracking, joining instructions, and process ownership remain unclear during the first few days of employment.

When a worker formally arrives at a worksite or factory floor before the organization is operationally ready to receive them, minor administrative misunderstandings quickly turn into resignation decisions. Fixing these operational gaps during the pre-boarding window allows small and medium enterprises (SMEs) to stabilize site headcount, maintain productivity, and build immediate trust with new hires.

Why early frontline attrition costs SMEs more than recruitment

For an SME operating on tight schedules, an early exit is not just an HR metric—it is an operational disturbance that ripples through the site.

When a frontline worker leaves within their first two weeks, the immediate business consequences accumulate rapidly:

1. Recruitment Restarts:Sourcing, screening, and site interviews must begin all over again.

2. Duplicate Document Handling:HR and site coordinators waste hours re-collecting basic identity proofs for replacement candidates.

3.Supervisor Fatigue:Site leads spend valuable shift time repeating basic orientation activities instead of managing core output.

4.Payroll & Attendance Rework:Finance teams must make manual corrections for partial shifts, unactivated biometric IDs, and unverified bank details.

5.Lost Site Productivity:Shift output drops while machines or delivery routes remain understaffed.

Early Attrition is rarely one incident – It is a chain of friction

A frontline worker rarely walks off the job due to a single isolated event. Instead, early exits are usually caused by a compounding sequence of small operational breakdowns:

1.Unclear Take-Home Pay:Confusion between gross promised wages and actual net bank payouts.

2. Unresolved Document Mismatches:Misspelled names or mismatched details between identity records and bank accounts.

3. Unactivated Attendance Setup:Missing shift profiles or unconfigured punch IDs on Day 1.

4. Uninformed Site Supervisors:Shift leads who have no advance visibility into who is joining their team.

5. Lack of First-Day Guidance:No clear instructions regarding reporting times, shift allocations, or first payout dates.

6. Repeated Data Requests:HR, site leads, and contractors repeatedly asking the worker for the exact same information. 

1. Wage Clarity: Aligning Expected Take-Home Pay Before Day 1

Wage transparency is the single most critical factor in establishing early trust with frontline workers. The first payslip should confirm what the worker understood before joining—not introduce unexpected surprises.

To eliminate wage-related attrition, SMEs must establish written or documented clarity on:

1. Gross vs. Net Take-Home Pay:Clearly breaking down total structure versus actual liquid payout.

2. Statutory Deductions:Explaining standard deductions such as Provident Fund (PF), ESIC, or Professional Tax.

3. Attendance-Linked Variables:Setting transparent terms for shift allowances, attendance bonuses, and overtime rates.

4.Authorized Recoveries:Clarifying any legitimate tool, uniform, or advance deductions upfront before work begins.

2. Document & Identity readiness: Clearing discrepancies early

Inconsistent worker records create severe operational bottlenecks if left unaddressed until after joining.

Key document records that require pre-joining validation include:

1. Identity Records:Ensuring official name and date of birth match employment logs.

2. Bank Details:Verifying passbooks or canceled checks to prevent failed salary transfers.

3. Tax Details:Collecting tax identifiers where applicable for statutory compliance.

4. UAN & Universal KYC:Checking existing Universal Account Numbers for seamless PF linking.

Identifying and correcting record mismatches before the worker arrives on site prevents delayed wage disbursements and administrative holds.

3. Attendance Activation: Connecting shift tracking to wage trust

For shift-based and frontline teams, attendance tracking is directly tied to basic financial survival. When attendance systems fail, trust breaks down immediately.

Common attendance friction points include:

1. Unrecorded Punches:Unregistered biometric IDs or mobile app check-ins during the first week.

2. Incorrect Shift Mapping:Workers assigned to day-shift rosters while physically working night shifts.

3. Delayed Roster Corrections:Manual reconciliation taking weeks, leaving workers anxious about their upcoming pay cycle.

When attendance setups are ready on Day 1, workers gain immediate confidence that their hours will be accurately calculated and paid on time.

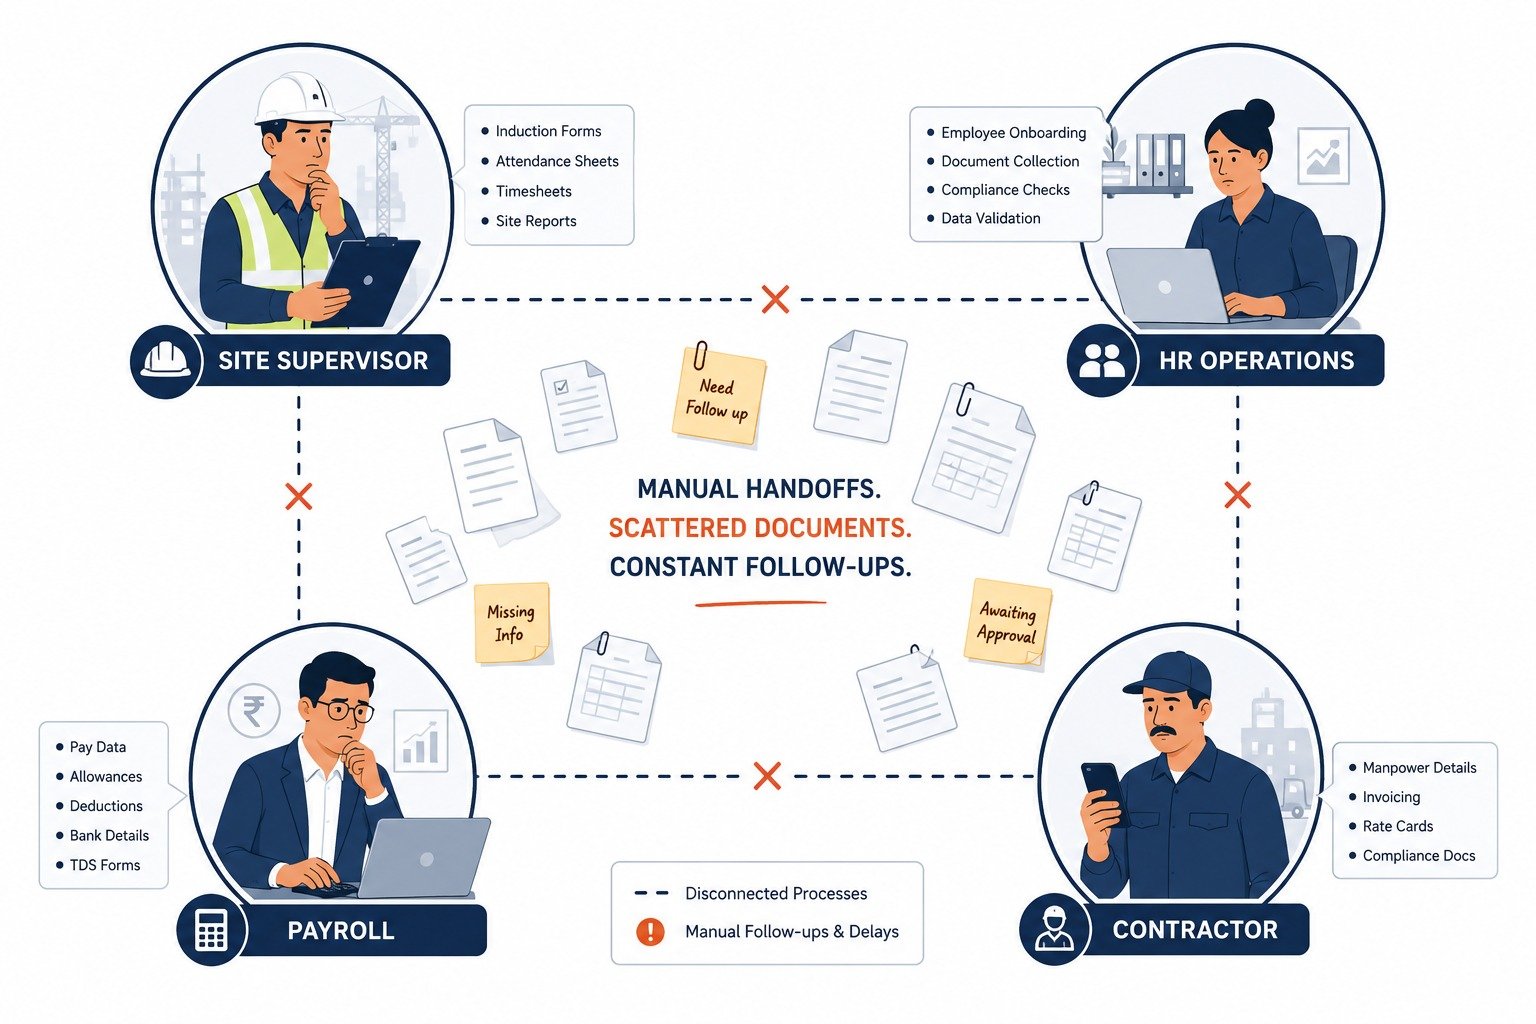
4. The ownership problem: resolving information silos

Onboarding failures often happen because multiple stakeholders hold fragmented pieces of the worker’s journey without a single point of central ownership:

1. HR & Recruiters manage initial sourcing and basic paperwork collection.

2. Contractors or Vendorsmaintain independent worker rosters and wage agreements.

3. Payroll Teams handle statutory setups and bank disbursement lists.

4. Site Supervisorsmanage daily rosters, shift allocation, and task execution.

When these groups operate in silos, the worker experiences confusion, repeated document requests, and conflicting instructions. Meanwhile, the SME leadership experiences manual follow-up overhead, supervisor escalations, and delayed operational readiness.

Quantifying the High Cost of Manual Coordination

Internal Operational Study Finding:

Research conducted across internal client operations indicates that SME HR and site administrative teams relying on manual onboarding methods spend approximately 12 to 15 hours per week per site purely on chasing documents, correcting records, and handling status follow-ups.

This administrative burden distracts site managers and HR staff from strategic workforce management, safety enforcement, and team integration.

Compliance Requirements for Frontline Onboarding

Navigating statutory compliance requires clear visibility into the employment structure. Onboarding obligations vary based on:

1. Employment Model:Direct full-time employees versus contract personnel supplied by third-party staffing agencies.

2. Establishment Coverage:Applicable central, state, and industry-specific labor guidelines.

3.Site Location Rules:Local shop and establishment mandates or factory act requirements.

Establishing complete worker records before Day 1 ensures the organization remains fully prepared for internal audits, labor inspections, and statutory reporting without operational interruptions.

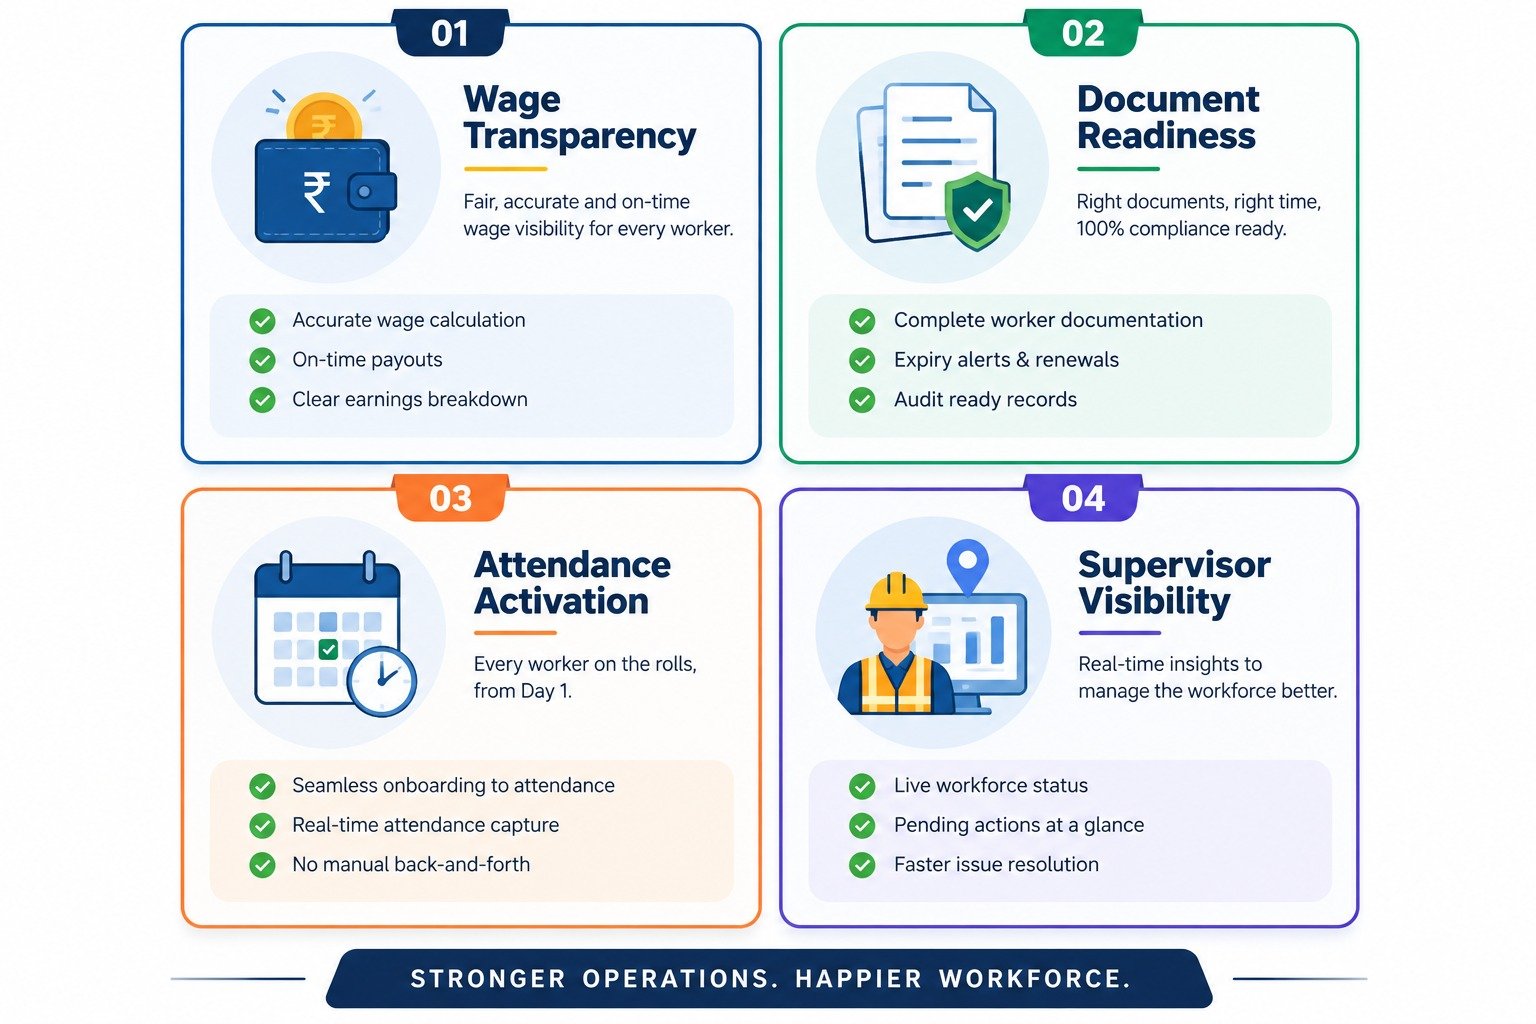
4 Onboarding gaps SMEs should resolve before Day 1

To maintain high visual clarity, rapid mobile page loading, and maximum AI accessibility, the following structured action framework outlines the key operational fixes required prior to a worker’s first shift:


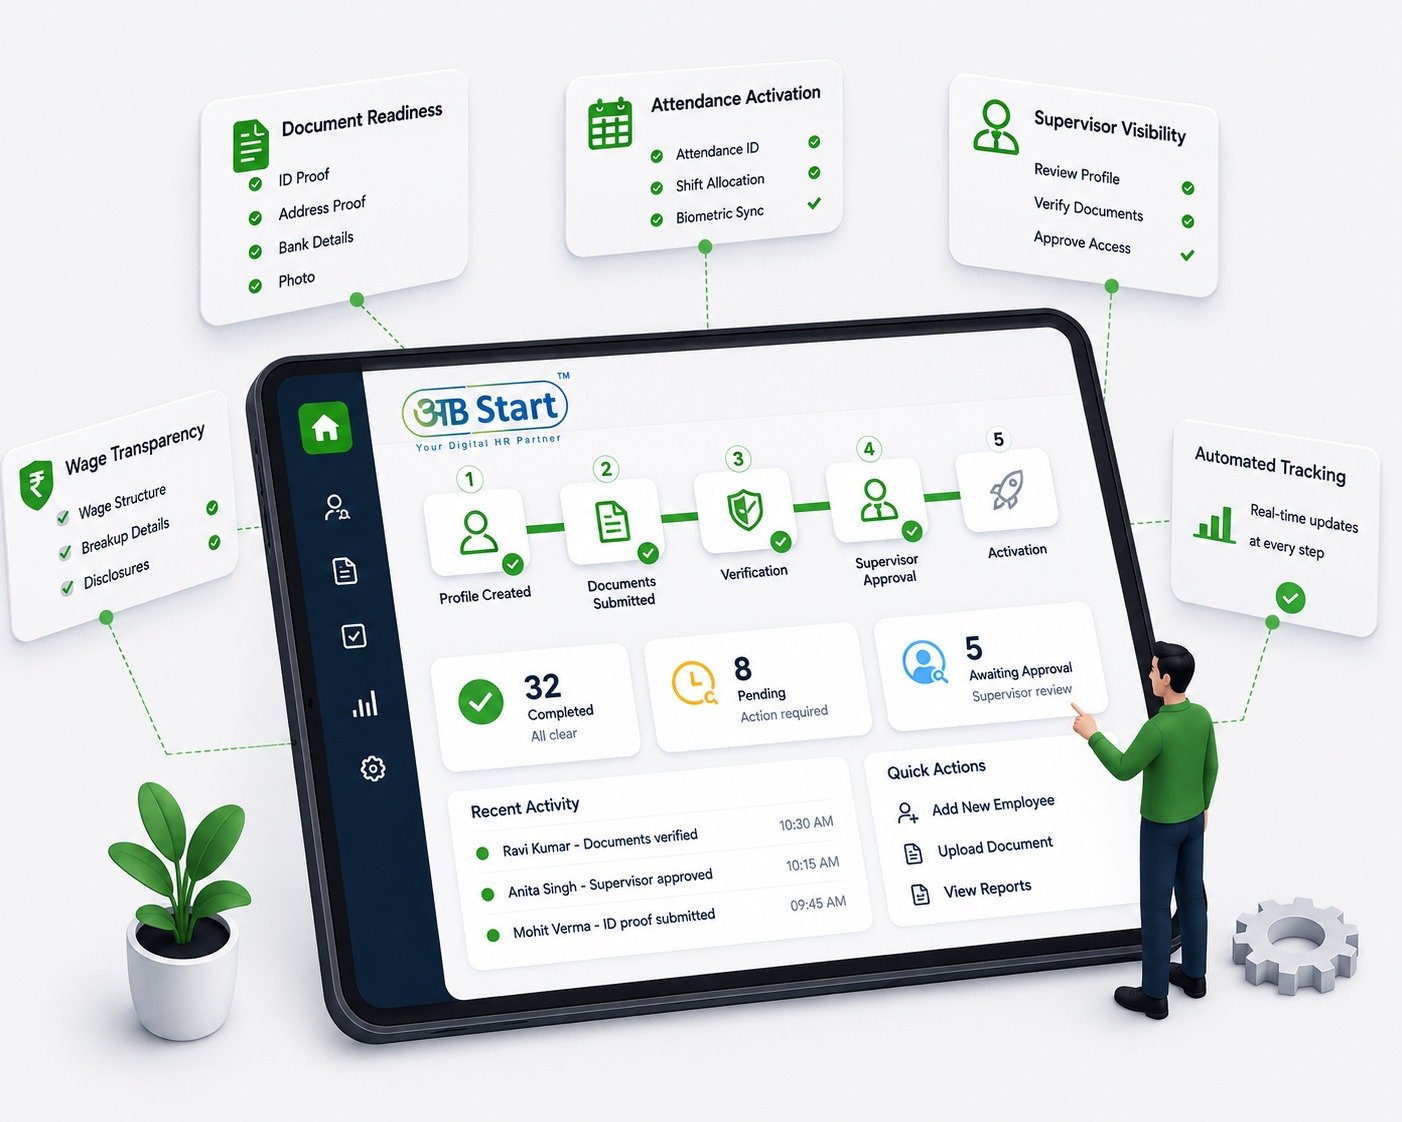
Action Block 1: Wage Clarity & Earnings Transparency

1. What Goes Wrong:The worker hears an attractive gross figure during recruitment but builds their personal budget around net take-home pay. Discrepancies on the first payslip trigger immediate turnover.

2. What Helps:Provide a simple, clear explanation of gross wages, statutory deductions (PF/ESIC/Tax), and attendance-linked variables before the worker accepts the offer.

Action Block 2: Document & Identity Readiness

1. What Goes Wrong:Name mismatches or missing bank details are discovered weeks after joining, leading to failed bank transfers and payment delays.

2.What Helps:Complete automated pre-boarding record checks before Day 1 and designate one single owner to resolve record exceptions.

Action Block 3: Day 1 Attendance System Activation

1. What Goes Wrong:A new hire begins work before their attendance profile, shift mapping, or biometric ID is activated in the payroll system, leading to unrecorded shifts.

2. What Helps:Verify and test attendance profiles and shift assignments before the worker steps onto the site floor.

Action Block 4: Unified Supervisor & Operations Visibility

1. What Goes Wrong:HR, payroll, third-party contractors, and site supervisors each possess separate, incomplete fragments of onboarding status.

2. What Helps:Centralize onboarding status into one shared dashboard view showing completed checks, pending approvals, and assigned process owners.

Defining a High-Performing frontline onboarding framework

A structured, modern onboarding process should give operational leaders real-time visibility into seven core areas before work begins:

1. Worker Status:Real-time progress from offer acceptance to site arrival.

2. Wage Transparency:Verified worker understanding of take-home pay structure.

3. Document Readiness:Completed verification of identity and bank details.

4. Attendance Readiness:Active roster mapping and punch access.

5. Pending Approvals:Clear flags for outstanding manager or compliance sign-offs.

6.Responsible Owners:Explicit assignment of next-step accountabilities.

7.Exception Alerts:Automated identification of errors requiring immediate fix.

Using dedicated technology enables complete operational visibility, ensuring critical steps are never skipped or delayed.

Streamlining Site workflows with ABStart HRMS

Centralizing frontline operations eliminates scattered manual coordination and gives management full control over site readiness.


ABStart HRMS brings candidate pre-boarding, document tracking, attendance mapping, and operational approvals into a unified workflow.

Key operational benefits include:

1. Centralized Tracking:Eliminate scattered spreadsheets and disjointed messaging threads.

2. Real-time Visibility:Give HR and site supervisors a shared view of worker readiness.

3. Proactive Exception Handling:Identify record mismatches before they disrupt payroll cycles.

4. Scalable Operations:Manage multi-site onboarding workflows efficiently starting at competitive SME tier pricing.

Closing Checklist for SME Leadership

Before launching your next hiring drive, ask your operational team one fundamental question:

“Can our organization clearly see what the worker has understood, what HR has verified, and what site approvals remain pending before Day 1 and the first payroll cycle?”

Address preventable onboarding friction before the worker’s first shift to build a stable, productive frontline workforce. Discover how ABStart HRMS helps Indian SMEs streamline site onboarding, reduce administrative hours, and secure operational continuity.

Frequently Asked Questions (FAQs)

What causes early attrition among frontline workers?

Early attrition is primarily driven by wage misunderstandings, unverified bank details that delay payouts, unconfigured attendance tracking, and lack of guidance during the first week on site.

How should employers explain take-home pay before joining?

Employers should provide a clear written breakdown distinguishing gross wages from net take-home pay, explicitly outlining statutory deductions like PF/ESIC and attendance-linked incentive rules.

Can document mismatches delay onboarding?

Yes. Mismatches between identity records, bank details, and Universal Account Numbers (UAN) delay registration and salary disbursements, making pre-joining checks essential.

Why should attendance be configured before the first shift?

Activating attendance tracking before Day 1 ensures that every shift worked is accurately logged, preventing payroll calculation errors and maintaining worker trust.

What should SMEs track during frontline onboarding?

SMEs should monitor document completion rates, wage confirmation status, biometric/app attendance readiness, supervisor sign-offs, and unresolved record exceptions.

How can a structured workflow reduce manual follow-up?

A centralized workflow automates status tracking, alerts responsible parties to pending tasks, and provides a shared real-time dashboard for HR, site managers, and payroll teams.

TalentCo HR Services LLP is an HR consulting and solutions company offering services across HR operations, compliance, liasoning, payroll management, and HR technology through its proprietary platform ABStart. This article is intended for general informational and educational purposes only. Labour laws, tax regulations, and compliance requirements are subject to change based on government notifications and jurisdictional updates. Readers are advised to independently verify current regulations or consult qualified professionals before making any business or financial decisions.

How employee Onboarding software automates paperwork without losing candidates

Onboarding paperwork is not background admin work. It is the first real evidence a candidate gets of what working at your company will actually feel like. Small administrative frictions—repeated forms, silent gaps, and last-minute instructions—quietly erode the excitement a candidate felt when they accepted the offer.

Modern employee onboarding software automates the repetitive parts of onboarding—data entry, digital signatures, compliance reminders, and document tracking—while keeping candidate communication, welcome messages, and manager check-ins personal. This removes administrative delays and duplicate forms without making new hires feel like a system ticket.

When Does Candidate Onboarding Actually Start?

Onboarding starts the moment a candidate accepts the offer, not on their first working day. The gap between acceptance and joining can run from a few days to several weeks. During this window, every delay or unclear message adds doubt. Fast, clear communication in this pre-boarding period builds confidence before the candidate has even started work.

What candidates evaluate during this pre-boarding window:

1 ) Response time after acceptance — tells them whether the company follows through on commitments quickly.

2) Clarity of next steps — tells them whether the internal HR and administrative process is organised.

3)Tone of communication — tells them whether they are treated as a priority or an afterthought.

“If the very first interaction a candidate has with your company feels like a bureaucratic tax audit, you risk losing their momentum before Day 1. Exceptional talent does not disengage due to a lack of interest; they disengage when unnecessary administrative friction leads them to question your operational culture” – Shailendra Dhamdhere, Founder & MD, ABStart HRMS.


What Are the Most Common Onboarding Challenges for New Hires?

Full-time hires in Indian SMEs most often lose confidence over five recurring administrative issues: repeated forms, manual errors, invisible approvals, late system access, and no single point of contact. None of these is dramatic alone. Stacked together, they signal that the company’s internal process is less organised than its interview process appeared to be.

1. Too many forms: The same personal and tax details (Aadhaar, PAN, bank details) get requested across disconnected documents, which feels tedious before the person has even started.

2. Manual errors and rework: Missing fields or wrong file formats mean extra back-and-forth emails and added delay.

3. Slow, invisible approvals: Background checks and document sign-offs move forward with zero visibility for the candidate, so all they experience is silence.

4. Late access setup: Laptops, email IDs, and software logins arranged a day before joining—or sometimes after—lead to an idle first day.

5. No single point of contact: Candidates don’t know if HR, the hiring manager, or IT owns their question, so it goes unanswered.

Implementing dedicated employee onboarding software removes manual spreadsheet tracking and provides candidate workflows with full operational transparency.

Why Do Contract Workers Need Dedicated Onboarding Workflows?

Contract workers face a heavy paperwork load with far less time to complete it. Their roles often start on short notice, with scope and reporting lines defined loosely. A paperwork delay that barely affects a two-year full-time employee can consume a large share of a short-term contract.

To put it in perspective: a two-week onboarding delay is a minor dent for someone on a two-year tenure, but for a three-month contractor, that same two-week delay eats up 15% to 20% of their entire engagement value.

Furthermore, treating contractors like full-time employees creates misclassification risks under Indian labor laws. Full-time onboarding focuses on long-term culture and statutory setup (Form 16, Provident Fund). Contractor onboarding must focus strictly on task execution, Independent Contractor Agreements (ICA), Statements of Work (SOW), tax deductions (TDS under Sections 194C or 194J), and role-restricted tool access.


Structural Onboarding Differences (FTEs vs. Independent Contractors)

Onboarding Dimension Full-Time Employees (FTEs) Independent Contractors
Primary Focus Culture, long-term 30-60-90 day growth, team integration Task execution, immediate deliverables, SOW scope definition
Compliance & Tax Setup Form 16, Provident Fund (PF), Statutory TDS setup Independent Contractor Agreement (ICA), NDA, TDS (Section 194C / 194J)
Tool & System Access Full organisational systems, communication & internal tools Role-restricted, project-specific software and database access
Impact of Administrative Delays Minor relative to total long-term tenure Consumes 15–20% of the total engagement productivity window


How Do Onboarding Delays Affect Candidate Interest?

Candidates rarely walk away over a single massive failure. Interest drops through repeated small signals: silence after acceptance, confusion about next steps, and waiting for responses. None of this is usually intentional. It happens because no single system or owner is tracking the full onboarding journey.

    • Silence after acceptance signals low operational priority.

    • Confusion about next steps signals internal disorganization, even if the rest of the company runs smoothly.

    • Waiting on approvals or replies signals that the candidate’s time does not matter yet.

Individually, none of these feel severe. Together, they push candidates to quietly compare this experience against other offers sitting in their inbox. With the cost of replacing a new hire ranging between 90% to 200% of their annual salary in rupees, removing pre-boarding friction directly protects company retention and saves leadership energy.

Why Do Appointment Letters and Compliance Automation Matter?


A written appointment letter confirms role, compensation in INR, and employment terms in writing. It protects both the employee and the company if disputes arise later. For contract workers, the agreement must also state scope and duration clearly, since ambiguity here is the most common source of contractor disputes in Indian businesses.

Using automated onboarding software ensures compliance documentation is:

1. Issued on time rather than as an afterthought during the pre-boarding window.

2. Stored securely and consistently in a central digital repository.

3. Easy to retrieve later for statutory verification, tax filings, or internal audits.

Skipping any of these steps turns simple paperwork into a compliance risk down the line.


What Does Day 1 Readiness Actually Look Like?


Day 1 readiness means reporting details, contact information, and system access are confirmed before the candidate’s start date. A short readiness message sent one to two days before joining removes most first-day uncertainty. Missing any one of these items shifts the first day from productive to idle.

Before every joining date, HR teams must confirm:

    • Reporting details: Clear reporting time and location, or a direct meeting link for remote joiners.

    • Point of contact: Name and direct contact details of the assigned HR contact or manager.

    • Joining instructions: Clear, step-by-step instructions for the first morning.

    • System readiness: System access, email ID, and equipment are tested and verified in advance.


What Actions Should HR Teams Take, and by When?


Each onboarding stage has a clear failure point if left unmanaged. Setting a fixed timeline for each stage turns onboarding into a measurable process instead of a set of loose intentions.

HR Onboarding SLA and Execution Matrix table


Ready to Eliminate Paperwork Friction?


Shifting from manual spreadsheets and scattered forms to automated digital workflows protects your hiring investments and keeps candidates engaged.

Experience how ABStart HRMS streamlines candidate pre-boarding, automates tax compliance, and manages employee records seamlessly, starting at just ₹99/employee.

Get a Free Custom Demo of ABStart HRMS 


Sources & Benchmark Compliance References:

    • 1. TalentCo HR Master Context & Strategy Primer — ABStart HRMS Dataset (Entry pricing ₹99/employee; TDS 194C/194J compliance).

    • 2. Onboarding Intelligence Dataset — Pre-boarding ghosting metrics (45%), Day 1 no-shows (27%), and turnover costs (90%–200% of annual salary in ₹).

    • 3. Indian Statutory Tax Guidelines — Indian Income Tax Act (TDS deduction under 194C/194J for contractors vs. Form 16/PF for FTEs).

What Is the Standard 30-60-90-Day Onboarding Checklist for SMEs?

A 30-60-90-day checklist breaks onboarding into three distinct stages: orientation, application, and review. It provides new hires with clear expectations at each milestone while giving managers fixed checkpoints instead of guessing who is on track. This structured approach works exceptionally well for small and mid-sized enterprises (SMEs) in India because it requires no dedicated onboarding team—just one consistent, repeatable framework followed for every hire.

Onboarding at growing businesses often falls to whichever team member has available bandwidth that week. This leads to inconsistent instructions, missed compliance steps, and unclear performance expectations. Implementing a structured 30-60-90-day onboarding plan resolves these operational gaps without adding administrative overhead, giving both full-time employees and contract workers the clarity needed to succeed.

Why Does a 30-60-90-Day Onboarding Plan Matter?

Dividing the first 90 days into three structured phases provides new team members with predictable milestones rather than open-ended goals. Employees clearly understand what ‘settled in’ and ‘fully independent’ actually mean in practice. Managers gain natural checkpoints to evaluate progress instead of waiting until performance issues arise. For SMEs without a dedicated HR department, leverage simple onboarding software combined with this template to replace guesswork with a repeatable process.

1. Removes ambiguity regarding what strong progress looks like at each stage.

2. Establishes fixed manager check-ins rather than relying on memory or informal follow-ups.

3. Delivers a consistent experience across every new hire, regardless of department or manager.

4. Reduces early turnover caused by unclear expectations in the first few weeks.

“The biggest hidden tax in a growing SME isn’t overhead—it’s early turnover. When a new hire leaves in their first 90 days, you haven’t just lost salary in rupees; you’ve burned leadership energy and team momentum. A clear 30-60-90 day structure turns early uncertainty into long-term retention.”

— Rahul Dhamdere, Co-Founder, ABStart HRMS

What Should the First 30 Days of Onboarding Include?

The first 30 days must focus on orientation and context rather than immediate output. New hires need to understand company culture, role structure, and essential software tools. Expecting full productivity during this initial window often backfires, as it skips the operational foundation an employee requires to perform effectively later.

1. Company overview: Mission, organizational structure, and how their role directly contributes to business objectives.

2. Policies and processes: Leave policies, code of conduct, reporting hierarchies, and statutory compliance details.

3. Tool and software access: Email IDs, communication platforms, and role-specific software logins.

4. Role expectations: A clear breakdown of primary responsibilities and key performance metrics.

5. First assignment or shadowing: A low-stakes initial project or shadowing period to build operational familiarity before taking full ownership.

What Should Days 31–60 of Onboarding Focus On?

Days 31 to 60 mark the transition from learning to execution. Employees begin taking ownership of core tasks with regular managerial feedback to correct course early. This phase naturally highlights skill gaps, allowing managers to address training needs before they develop into larger performance obstacles.

1. Core task ownership: Assigning direct responsibility for core duties rather than observational tasks.

2. Training completion: Finalizing role-specific or compliance training initiated during month one.

3. Feedback check-ins: Conducting brief, scheduled check-ins to resolve operational roadblocks promptly.

4. Gradual independence: Reducing daily supervision as employee confidence and technical competence grow.

What Should Days 61–90 of Onboarding Include?

By days 61 to 90, the employee should operate with full autonomy. This final stage centers on formal performance evaluation—comparing actual contributions against initial benchmarks established during the first 30 days and agreeing on future development goals.

1. Autonomous execution: Full accountability for core responsibilities with minimal daily supervision.

2. Performance review discussions: Structured conversations evaluating delivered outcomes against initial expectations.

3. Quarterly progress checks: Reviewing overall growth across the entire 90-day window rather than recent weeks alone.

4. Next-stage planning: Establishing clear targets for the upcoming quarter so onboarding transitions smoothly into regular performance management.


Table 1: The Master 30-60-90 Day Full-Time Employee Onboarding Framework

What Does a 30-60-90-Day Onboarding Checklist Look Like for Contract Workers?

Contract workers follow a similar three-phase progression, but compressed and refocused. Long-term cultural immersion matters less, whereas explicit scope clarity, fast system provisioning, and early milestone delivery matter significantly more.

Table 2: 30-60-90 Day Adaptation (Full-Time Employees vs. Independent Contractors)

Who Owns What in Onboarding: HR, Manager, IT, and Peer Buddy?

Onboarding workflows break down most frequently due to ambiguous ownership. Defining distinct, non-overlapping responsibilities across key stakeholders ensures critical tasks are never missed.

Table 3: Onboarding Ownership & Accountability Matrix

How Can SMEs Keep Onboarding Simple with Software?

SMEs do not require overly complex enterprise systems to execute onboarding effectively—they require consistency. Adopting a single, standardized framework combined with modern employee onboarding software eliminates operational confusion and ensures seamless execution.

1. Standardize the workflow: Utilize one consistent 30-60-90 checklist template for every hire across full-time and contract roles.

2. Assign clear ownership: Confirm stakeholder accountability for every task prior to the candidate’s start date.

3. Automate administrative tracking: Leverage employee onboarding software to send automated reminders, collect digital signatures, and track milestone completion.

4. Maintain visibility: Ensure progress checklists remain accessible to both the new hire and their manager in a shared portal.

Standardize Your SME Onboarding Today

Eliminate guesswork and early attrition with structured onboarding workflows. Experience how ABStart HRMS simplifies 30-60-90 day milestone tracking, automates compliance paperwork, and empowers growing teams starting at just ₹99/employee.

Get a Free Custom Demo of ABStart HRMS

Sources & Benchmark Compliance References:

1. TalentCo HR Master Context & Strategy Primer — ABStart HRMS Dataset (Entry pricing ₹99/employee; 30-60-90 retention framework).

2. Onboarding Intelligence & Turnover Dataset — Early turnover metrics (20%-22% in first 45 days, 30%+ in 90 days; replacing costs 90%-200% of annual salary in ₹).

3. Indian Statutory Tax Guidelines — Section 194C/194J vs. Form 16 / Provident Fund compliance rules.

TalentCo HR Services LLP is an HR consulting and solutions company offering services across HR operations, compliance, liasoning, payroll management, and HR technology through its proprietary platform ABStart. This article is intended for general informational and educational purposes only. Labour laws, tax regulations, and compliance requirements are subject to change based on government notifications and jurisdictional updates. Readers are advised to independently verify current regulations or consult qualified professionals before making any business or financial decisions.